Blog

  • The Modern Agency’s Cross-Border Playbook: How to Cut 4% in Hidden Wire & FX Fees

    The Modern Agency’s Cross-Border Playbook: How to Cut 4% in Hidden Wire & FX Fees

    Introduction: The Anatomy of a $100,000 Invoice

    Imagine your digital agency closes a $100,000 retainer with an enterprise client in the United States or the UAE. Your team delivers exceptional work, the client approves the invoice, and their accounts payable department initiates a standard SWIFT wire transfer.

    Five business days later, you check your company bank balance.

    Instead of $100,000, you find $96,150.

    Where did the remaining $3,850 vanish?

    It didn’t disappear due to project scope creep or late payment penalties. It was quietly siphoned off by legacy banking architecture: an opaque foreign exchange (FX) spread, intermediary routing fees, and forced currency conversions.

    For scaling creative, software development, performance marketing, and remote staffing agencies, this is not an isolated incident—it is a recurring monthly tax. If your agency bills $1.5M to $3M annually from overseas clients, you are quietly handing $60,000 to $120,000 of pure net profit to correspondent banks every single year.

    In this operational playbook, we break down the exact mathematics behind these hidden margin leaks and outline how top-performing global agencies are rebuilding their financial stacks around modern, unified multi-currency infrastructure.


    Part 1: The 3 Hidden Leaks Draining Agency Margins

    Traditional retail and commercial banks were built for local, domestic commerce. When applied to modern cross-border agencies managing global clients and distributed talent, their infrastructure breaks down into three costly friction points:

    1. The “Invisible” FX Spread (Loss: 2.5% – 4.0%)

    Most agency owners believe bank wire fees are limited to the flat $25 or $45 fee stated on their account statement.

    The real margin killer is the foreign exchange markup.

    Traditional banks rarely execute currency conversions at the real, interbank mid-market rate. Instead, they mark up the exchange rate by 2.5% to 4.2% above the true market price. When an overseas client sends USD to an agency bank account denominated in EUR, GBP, or AED, the receiving bank automatically force-converts the entire amount at their retail rate before depositing the funds.

    On a $50,000 invoice, a 3% hidden spread costs your business $1,500 in pure margin on a single transaction.

    2. The Intermediary Correspondent Chain (Loss: $35 – $75 per wire)

    The legacy SWIFT network operates like a flight itinerary with multiple layovers. Because your local bank rarely holds a direct relationship with your client’s overseas bank, the payment must hop through 2 to 3 intermediary correspondent banks.

    Each intermediary bank deducts a processing fee directly from the principal amount without providing transparency or itemized receipts. The result? Your client insists they sent the full amount, but your balance arrives short—triggering awkward invoice reconciliation emails between finance departments.

    3. The 4-Day Working Capital Freeze

    Cross-border wires frequently take 3 to 5 business days to settle. During this transit window, your capital is locked in clearing-house limbo.

    For agencies operating on tight payroll schedules—where media buying budgets must be funded daily and remote contractors expect payment every Friday—this settlement delay restricts cash flow velocity and forces agencies to maintain expensive cash buffers.


    Part 2: The Distributed Contractor Payroll Nightmare

    The margin leak doesn’t stop at client collections. Once funds finally land, modern agencies face the second half of the cross-border gauntlet: paying international talent.

    Modern agency teams are rarely confined to a single city. A performance marketing agency based in Dubai or London might employ:

    • 12 developers in Eastern Europe and Egypt
    • 8 media buyers in Latin America
    • 6 UI/UX designers in Southeast Asia

    Executing payroll across this distributed roster under traditional banking rails creates an operational nightmare:

    • Manual Entry Fatigue: Finance managers spend 4 to 6 hours every pay cycle manually inputting individual IBANs, SWIFT codes, and recipient addresses into traditional banking portals.
    • Double Conversion Penalties: Funds converted from USD into local agency currency are then converted againinto contractors’ local currencies—subjecting the agency to a second layer of FX markups.
    • Delayed Payouts: Freelancers frequently experience unexpected holds or rejections by local receiving banks, leading to team frustration and administrative firefighting.

    Part 3: The 4 Rules of the Modern Cross-Border Agency Stack

    High-growth agencies that protect their profit margins have abandoned disconnected legacy banks. Instead, they operate through a unified financial operating layer.

    The Unified Agency Money Flow Infographic - Cyrafa
    The Unified Agency Money Flow: From Multi-Currency Collections to Global Contractor Payouts

    Here are the 4 fundamental rules of modern agency finance:

    Rule 1: Never Force-Convert Client Retainers

    Never allow a bank to automatically convert incoming foreign payments.

    With Cyrafa Business Accounts, your agency receives dedicated multi-currency accounts and virtual IBANs in key commercial currencies—including USD, EUR, and AED.

    When an American client pays you $30,000, you receive $30,000 in your USD balance. When a GCC client settles an AED 100,000 contract, it lands directly in your AED account. You maintain complete control over when, how, and how much currency to convert.

    Rule 2: Eliminate the Middleman via Direct Routing

    By utilizing modern settlement rails and regulated infrastructure, payments move through direct clearing paths rather than labyrinthine correspondent chains. Invoices arrive in full, eliminating reconciliation discrepancies and unnecessary third-party deductions.

    Rule 3: Automate Contractor Payroll with 1-Click Batch Payouts

    Instead of paying 30 contractors individually, modern agencies upload a single CSV file or trigger a payout workflow:

    • Select recipient currencies (local fiat or stablecoins like USDT).
    • Review clear, upfront exchange rates.
    • Slide to transfer and settle all payouts simultaneously in minutes.

    What previously consumed half a business day of manual data entry is reduced to a 120-second operational routine.

    Rule 4: Consolidate Treasury into One Operating Layer

    When client collections, multi-currency balances, FX conversions, and outgoing contractor payouts live inside a single dashboard, the CFO gains real-time visibility over cash runway, pending receivables, and net operating margins.


    Part 4: Real-World Economics: Legacy Bank vs. Cyrafa

    To illustrate the bottom-line difference, consider an agency with $60,000 in monthly international collections and $30,000 in monthly remote contractor payouts:

    Operational Metric Legacy Banking Rail Cyrafa Unified Operating Layer Monthly Agency Savings
    Incoming Wire Fees $45 – $70 per wire Transparent, minimal inbound +$150 / mo
    Client FX Conversion (3.2%) -$1,920 on $60k volume Transparent wholesale spread (0.3%) +$1,740 / mo
    Contractor Payroll Fees (25 Wires) $35 x 25 = $875 1-Click batch payout rail +$650 / mo
    Settlement Velocity 3 to 5 business days Instant / Same-day settlement Cash Flow Velocity
    Finance Team Hours Spent 16 hours / month Under 1 hour / month 15 Hours Saved
    Annual Financial Impact Total Leak: $35,000+ / yr Retained Margin: Direct Net Profit +$30,480 / year

    Part 5: Institutional Trust & Regulatory Security

    When choosing an operating layer for your agency’s working capital, compliance and fund safety are non-negotiable.

    Cyrafa LLC is registered with the U.S. Department of the Treasury Financial Crimes Enforcement Network (FinCEN) as a Money Services Business (MSB), Registration No. 31000307129357.

    All account, payment, and settlement workflows operate under approved compliance, anti-money laundering (AML), and know-your-business (KYB) frameworks designed specifically for cross-border enterprise operations.


    Conclusion: Move Money Without Complexity

    In a competitive market where digital agencies compete on innovation, quality, and margins, losing 4% of your top-line revenue to legacy banking friction is a handicap your business cannot afford.

    Your clients are global. Your talent is global. Your financial stack should be too.

    One platform. Everything in motion.


    Ready to eliminate cross-border friction?

  • How to Build a Finance Stack for Marketing Agencies Working Across Crypto and Fiat

    How to Build a Finance Stack for Marketing Agencies Working Across Crypto and Fiat

    Marketing agencies rarely start with a complex finance stack. Most begin with a single business account, a payment link, and maybe a spreadsheet to track who owes what. That setup works until the client mix changes. One brand wants to pay in USDT, another insists on SWIFT transfers in USD, and a third needs AED invoices settled through a local IBAN. Suddenly, the agency is managing money across three rails, four currencies, and five different login screens — none of which talk to each other.

    The result is not just operational friction. It is invisible leakage: missed exchange windows, duplicate reconciliation work, delayed contractor payouts, and compliance gaps that only surface during an audit or a client’s vendor review. For agencies scaling past ten active clients or crossing borders regularly, the finance stack stops being back-office infrastructure and becomes part of the service delivery itself.

    This guide walks through how to design a finance stack that actually matches how modern marketing agencies operate — not how traditional banks assume they should.

    Why Agency Finance Is Different From Other B2B Services

    Marketing agencies sit in an awkward middle ground. They are not SaaS companies with predictable subscription revenue, nor are they trading desks with high-frequency settlement needs. Their cash flow is project-based, their payables are global and irregular, and their clients span industries with wildly different payment expectations.

    Three structural realities shape what an agency needs from its finance stack:

    Revenue arrives in multiple forms. A retainer might come via bank transfer, a performance bonus in stablecoins, and a one-off campaign fee through a corporate card reimbursement. Treating all inbound funds as if they arrive on the same rail creates reconciliation debt that compounds monthly.

    Payables are more diverse than receivables. Agencies pay freelancers in twelve countries, settle media buys in USD, cover software subscriptions in EUR, and sometimes need to disburse influencer fees in crypto. Each payable type has its own optimal rail, but most stacks force everything through one expensive default.

    Clients audit vendors more aggressively now. Enterprise brands and regulated advertisers increasingly require proof of compliant fund handling, clear transaction trails, and role-based access controls. An agency’s finance stack is no longer just about moving money — it is part of winning and retaining contracts.

    Ignoring these realities means building a stack optimized for simplicity rather than fit. The cost shows up as wasted margin on FX, delayed payments that strain freelancer relationships, and manual processes that do not scale when the agency adds its next five clients.

    The Four Layers Every Agency Finance Stack Needs

    A functional finance stack for a cross-border marketing agency is not a single product. It is four connected layers, each solving a distinct problem:

    1. Collections and Inbound Settlement

    The first layer handles how money comes in. For agencies, this means supporting at minimum: business IBANs for fiat collections, crypto deposit addresses or on-ramps for stablecoin payments, and SWIFT capability for larger international transfers.

    The critical detail is not just having these rails available — it is having them connected to the same operational view. When a USDT payment lands and a EUR wire arrives on the same afternoon, the team should see both in one place without exporting CSVs from separate dashboards. Disconnected inbound rails create the exact reconciliation gap that causes agencies to miss revenue recognition deadlines or double-count receipts during month-end close.

    2. Treasury and Conversion

    Once funds are collected, the second layer manages what happens before money goes out. This includes holding balances in multiple currencies, converting between crypto and fiat at controlled rates, and maintaining visibility into total liquidity across all accounts.

    For agencies, treasury management is less about speculation and more about predictability. If a client pays in USDT but contractors need to be paid in USD, the conversion timing directly affects margins. A stack that lets the agency hold, convert, and route funds within the same environment — rather than sending crypto to an exchange, withdrawing fiat to a bank, then initiating payouts — removes two to three days of settlement latency and eliminates at least one set of transfer fees per cycle.

    3. Payouts and Disbursements

    The third layer is where most agency finance stacks break down. Paying a local employee via payroll software is straightforward. Paying fifteen freelancers across Southeast Asia, Latin America, and Eastern Europe — some preferring bank transfers, others wanting stablecoins, a few needing mobile money — is a different problem entirely.

    Bulk payout functionality matters here, but so does rail flexibility. The ability to batch-disburse across SWIFT, local IBANs, and crypto wallets from a single interface reduces operational overhead dramatically. Equally important is having payout status visibility that finance and operations teams can share without forwarding screenshots or building custom trackers. When a freelancer asks “did my payment go through?”, the answer should be retrievable in seconds, not hours.

    4. Controls, Compliance, and Audit Readiness

    The fourth layer is the one agencies tend to add last and regret first. Role-based permissions, approval workflows, and immutable transaction records are not luxuries for enterprise clients — they are baseline expectations for any agency handling significant ad spend or operating across jurisdictions.

    Built-in compliance tooling also protects the agency from itself. When the person who approves invoices is also the person who initiates payouts, fraud risk increases regardless of intent. Separating these functions within the same platform — rather than relying on informal trust or external sign-off chains — creates an operational control model that scales with headcount and survives staff turnover.

    Common Mistakes Agencies Make When Upgrading Their Stack

    Even when agencies recognize the need for a better finance stack, implementation often stumbles on predictable missteps:

    Optimizing for the cheapest individual transaction instead of total cost of operations. A provider with low transfer fees but no integrated treasury forces manual conversions elsewhere, eating back savings through worse FX rates and additional withdrawal charges. Evaluate the full workflow cost, not the headline fee.

    Adding tools without connecting them. Stacking a crypto wallet, a neobank account, and a payout platform without integration between them recreates the original fragmentation problem with more logins. Prioritize platforms that unify rails natively or offer reliable API connections over assembling best-in-class point solutions that cannot communicate.

    Deferring compliance configuration until after growth. Setting up roles, approvals, and audit trails retroactively is significantly harder than configuring them during initial setup. Agencies that wait until a client demands SOC 2 evidence or a regulator requests transaction records often discover months of unstructured data that cannot be cleanly reconstructed.

    Treating the finance stack as a CFO problem when it is an operations problem. In most agencies, the people feeling the pain of a broken finance stack are project managers, account leads, and operations coordinators — not the finance team alone. Involving operations early in stack selection ensures the chosen solution matches actual daily workflows rather than theoretical financial models.

    What to Look for in a Unified Platform

    If the goal is reducing fragmentation rather than adding to it, evaluate platforms against these practical criteria:

    Can you receive crypto and fiat into the same account structure without manual bridging? Can you convert between assets and initiate payouts without leaving the platform? Do role-based permissions and approval workflows ship as native features rather than third-party integrations? Is transaction history exportable and audit-ready by default, not as a premium add-on? Does the platform support the specific geographies and currency pairs your agency actually operates in — not just the ones listed on the marketing page?

    These questions filter out platforms designed for generic B2B use and surface those built for the operational reality of cross-border, multi-rail businesses like marketing agencies.

    Making the Transition Without Disrupting Active Clients

    Migrating a finance stack while running live campaigns requires sequencing. Start by routing new client collections through the new platform while keeping legacy systems active for existing payables. Run parallel reconciliation for one full billing cycle to validate accuracy before decommissioning old accounts. Communicate the transition to freelancers and vendors proactively — payment disruptions erode trust faster than almost any other operational failure.

    The objective is not a perfect cutover on day one. It is a controlled migration that preserves service quality while establishing the new stack as the operational source of truth. Agencies that attempt big-bang migrations during active campaign periods typically trade one set of problems for another.

    The Operational Payoff

    When the finance stack actually fits how an agency works, the benefits extend beyond efficiency metrics. Freelancer retention improves because payments arrive predictably. Client confidence grows because fund handling is transparent and auditable. Margin leakage from FX and fees becomes visible and manageable. And the operations team spends less time chasing transactions and more time supporting the work that generates revenue.

    For marketing agencies operating at the intersection of crypto and fiat, the finance stack is no longer infrastructure to tolerate. It is a competitive capability to build deliberately.


    Cyrafa provides unified business accounts for marketing agencies working across crypto, fiat, SWIFT, and IBANs — with built-in treasury, bulk payouts, and compliance controls in one platform. Book a strategy call to discuss your agency’s specific workflow.

  • Where Did the Payment Go? The Hidden Visibility Problem in Business Finance

    Where Did the Payment Go? The Hidden Visibility Problem in Business Finance

    A customer paid. The money should be somewhere in the business finance stack.

    But the finance team still has to open a provider dashboard, search an inbox, check a bank account, ask operations for an update, and look through a spreadsheet before it can answer one basic question:

    Where did the payment go?

    This problem is common in growing businesses. Payments move across accounts, currencies, providers, approval steps, conversion workflows, treasury decisions, and payouts. When each stage lives in a different system, the payment may have arrived, but its context is scattered.

    The result is a hidden visibility problem. The business can move money, but it cannot always see the full story of that money.

    What payment visibility actually means

    Payment visibility is more than seeing a transaction in a dashboard. It means being able to understand a payment from initiation to final record.

    A visible payment workflow should answer:

    • Who sent or requested the payment?
    • What is the business purpose?
    • Which account, currency, or asset is involved?
    • Who owns the next action?
    • Has the payment been reviewed or approved?
    • Is it initiated, processing, settled, or returned?
    • Where did the funds go after settlement?
    • Has the transaction been reconciled?

    When those answers are available in one connected context, finance and operations teams can act. When they are spread across several tools, every question becomes an investigation.

    The journey of one payment

    Consider a simple business payment. A customer sends funds. The payment provider receives it. The finance team tries to identify it. Someone checks whether it matches an invoice. A reviewer confirms the transaction. The funds may be converted, transferred to another account, allocated to treasury, or used for a payout.

    The journey may look like this:

    Customer -> Payment Provider -> Business Account -> Review -> Approval -> Settlement -> Treasury -> Payout -> Reconciliation

    Each arrow is a handoff. Each handoff can create a delay, a missing reference, or an ownership question.

    The payment itself is only one event. The operating work around it is what creates friction.

    Why visibility breaks down

    Too many provider dashboards

    Businesses often add a new provider for every new requirement: collections, crypto payments, international transfers, conversion, or payouts. Each provider may have its own status labels, references, and reporting view.

    The finance team then has to create its own connection between systems.

    Context lives in conversations

    Approvals and payment updates often happen in email threads or messaging channels. The decision may be clear to the people involved, but difficult for another team member to find later.

    References are inconsistent

    An invoice number, provider reference, internal payment ID, and bank statement description may all refer to the same transaction without using the same identifier.

    Collections and payouts are separated

    Incoming funds and outgoing payments may be owned by different workflows. That makes it harder to understand how today’s collections affect upcoming withdrawals, vendor payments, or treasury requirements.

    The balance is visible, but the obligation is not

    A business may see a balance without knowing what is already committed, pending, reserved, or needed for a payment that is about to move.

    The real cost of missing context

    Poor payment visibility creates more than extra administrative work.

    Slower decisions

    Teams wait for confirmations instead of acting from a shared status view.

    More manual follow-up

    Finance, operations, support, and providers ask each other for updates that should already be available in the transaction record.

    Reconciliation takes longer

    The team has to rebuild the path from the original payment to the final settlement before it can close the record.

    Client and partner communication becomes harder

    When the internal status is unclear, it is difficult to give a confident update about a deposit, withdrawal, payout, or settlement.

    Control becomes dependent on individuals

    If one person is the only person who knows where the payment is, the workflow is not easy to scale.

    A better way to follow the flow

    Start with one transaction map

    Choose a common payment journey and document every step. Include the source, destination, provider, owner, approval point, settlement status, and final record.

    This reveals where the business loses context.

    Give each payment a consistent identity

    Use a reference that can connect the request, provider event, account movement, approval, settlement, and accounting record. A consistent identity reduces the need to match transactions by guesswork.

    Make ownership visible

    Every stage should have a clear owner. The team should know whether the next action belongs to finance, operations, a reviewer, a provider, or the counterparty.

    Use shared status language

    Define what initiated, in transit, processing, settled, failed, returned, and reconciled mean in your operating model. Shared language prevents different teams from interpreting the same payment differently.

    Connect visibility to action

    A useful view should not only show what happened. It should help the team decide what happens next: approve, investigate, convert, settle, pay out, or reconcile.

    Where Cyrafa fits

    Cyrafa is designed for businesses that operate across crypto and fiat workflows and need a clearer business finance operating layer. Its platform pages cover Business IBANs, crypto payment workflows, crypto-to-fiat exchange, SWIFT transfers, treasury management, and payouts.

    These workflows are connected by the questions finance and operations teams ask every day: where did the money come from, where is it now, who can move it, what should happen next, and how should the transaction be recorded?

    Cyrafa can help businesses explore a more connected approach to accounts, payments, settlement, treasury, approvals, and payouts, subject to the business profile, onboarding review, supported products, and applicable terms.

    Corporate Cards are currently marked as Coming Soon and should not be presented as an available product.

    A practical visibility checklist

    Review your current payment operation and ask:

    1. Can the team locate a payment without checking several systems?
    2. Does every payment have a clear purpose and reference?
    3. Can finance see who owns the next action?
    4. Are approval decisions connected to the transaction?
    5. Can the team distinguish available, committed, and pending funds?
    6. Can collections, settlement, and payouts be viewed together?
    7. Does the final record preserve the complete payment history?

    If several answers are no, the business may not have a payment problem. It may have a visibility problem.

    Final takeaway

    The question “Where did the payment go?” should not require an investigation across inboxes, dashboards, spreadsheets, and messages.

    A stronger finance operation keeps the payment’s identity, owner, status, approval, destination, and final record connected. That gives the business a clearer way to move money and a more reliable way to understand it.

    Ready to see the full flow of your business money? Talk to the Cyrafa team.

  • How Forex Brokers Can Improve Payment Visibility and Payout Control

    How Forex Brokers Can Improve Payment Visibility and Payout Control

    For a forex broker, payments are part of the core operating model. Client deposits, withdrawals, partner settlements, introducing broker commissions, liquidity movements, and vendor payouts all need to move through a controlled process.

    As volume grows, payment operations can become difficult to manage. A broker may use different providers for collections, bank transfers, crypto payments, currency conversion, and payouts. The result is often limited visibility, manual status checks, and a finance team spending too much time connecting information across systems.

    Better payment operations begin with a simple question: can the broker clearly understand where every payment is, what it is for, who approved it, and what should happen next?

    Why payment visibility matters for forex brokers

    Payment visibility means having enough context to follow a transaction from initiation to settlement. It includes the payment status, currency, counterparty, destination, owner, and next action.

    For a forex broker, this context supports several daily processes:

    • Monitoring client deposits
    • Tracking withdrawal requests
    • Managing partner and introducing broker payments
    • Coordinating liquidity and treasury movements
    • Investigating payment delays
    • Supporting reconciliation and reporting

    Without a clear view, operations teams may need to check multiple provider dashboards, inboxes, spreadsheets, and internal messages to answer a single client or finance question.

    Common payment challenges in brokerage operations

    Multiple collection channels

    Clients may deposit through bank transfers, payment gateways, or digital asset payment workflows. Each route can have different references, settlement timing, and information requirements.

    Withdrawal status uncertainty

    A withdrawal request may pass through review, approval, processing, and settlement. When each stage is tracked separately, support and operations teams can struggle to give a consistent status update.

    Manual payout approvals

    Brokerages often need controls around withdrawals, partner commissions, and vendor payments. If approvals happen through scattered email or messaging threads, the process becomes harder to audit and easier to delay.

    Reconciliation across systems

    The finance team may need to match a client or partner reference with a provider record, a bank statement, an internal ledger, and a final settlement entry. The more disconnected the systems, the more manual this work becomes.

    Different currencies and rails

    International brokerage operations can involve multiple currencies and transfer methods. The team needs to understand not only the balance, but also which funds are available, pending, committed, or required for upcoming payouts.

    A clearer payment operations workflow

    1. Capture the payment context

    Every payment should carry enough information to identify its purpose. Useful context can include the client or partner reference, currency, payment route, destination, and internal owner.

    The more context captured when the payment starts, the less time the team spends searching for it later.

    2. Separate review from execution

    A clear workflow distinguishes between a request, a review, an approval, and the final payment. This helps define who can perform each action and creates a more understandable transaction history.

    3. Track settlement status

    Operations teams should be able to distinguish between initiated, in transit, processing, settled, and failed or returned transactions. Clear status language improves internal coordination and makes client communication more consistent.

    4. Connect collections and payouts

    Collections and payouts are often managed by different teams, but they affect the same liquidity position. A connected view helps the business understand how incoming funds support withdrawals, partner payments, and treasury requirements.

    5. Reconcile the full record

    The final record should connect the original request, approval decision, provider reference, settlement result, and internal accounting entry. This creates a more reliable basis for reporting and review.

    Questions a broker should ask about its current setup

    1. Can the team see the status of a client deposit without checking several systems?
    2. Are withdrawal approvals recorded in a consistent workflow?
    3. Can operations identify the owner of the next action?
    4. Are partner commissions and vendor payouts tracked with clear references?
    5. Can the finance team connect the original payment to the final settlement?
    6. Does the treasury view show available, pending, and committed funds?
    7. Can the process support both fiat and crypto-related payment workflows where required?

    If the answer to several questions is no, the issue may be the operating structure around the payment providers rather than one individual payment rail.

    How Cyrafa fits into broker payment operations

    Cyrafa is positioned as a business finance platform for companies that operate across crypto and fiat workflows. Its platform pages cover Business IBANs, crypto payment workflows, crypto-to-fiat exchange, SWIFT transfers, treasury management, and payouts.

    For a forex broker, these capabilities can be considered as connected parts of a broader payment operation: collecting business funds, managing settlement routes, organizing treasury visibility, and supporting controlled payouts.

    Cyrafa can help businesses explore a clearer operating layer around their existing money flows, subject to the business profile, onboarding review, supported products, and applicable terms.

    Corporate Cards are currently marked as Coming Soon and should not be treated as an available brokerage payout or spend product.

    Practical steps to improve control

    Start by mapping the broker’s most important payment journeys: client deposit, client withdrawal, partner commission, vendor payout, and treasury transfer. For each journey, record the owner, approval point, provider reference, settlement destination, and reconciliation requirement.

    Next, standardize the status language used by finance, operations, support, and payment providers. A shared vocabulary reduces confusion when a payment moves between teams.

    Finally, keep payment context, approvals, settlement status, and transaction history as close together as possible. A connected workflow reduces repeated follow-up and gives decision-makers a clearer view of what needs attention.

    Final takeaway

    Forex brokers need more than payment rails. They need a clear operating process around those rails.

    Better visibility helps teams follow deposits, withdrawals, settlements, commissions, and payouts with less manual effort. Clear approvals and connected reconciliation help the business maintain control as transaction volume and international activity grow.

    For brokers managing fiat and crypto-related flows, the right finance operating layer can make payment operations easier to understand, review, and scale.

    Want to review your broker payment workflow? Talk to the Cyrafa team.

  • Crypto-to-Fiat Settlement: A Practical Guide | Cyrafa

    Crypto-to-Fiat Settlement: A Practical Guide | Cyrafa

    Crypto-to-fiat settlement is the process of turning digital asset balances into payout-ready fiat with a known destination, a known timing, and a clear record trail. For a crypto business, it is one of the most repeated workflows in finance: revenue arrives in USDT or USDC, and obligations — payroll, suppliers, software, taxes — leave in fiat.

    The conversion itself is rarely the hard part. The hard part is everything around it: deciding when to convert, who approves it, where the fiat lands, how the rate and fees are recorded, and how the transaction reconciles at month-end. When those answers live across an exchange account, a bank account, and a spreadsheet, settlement becomes an operational risk instead of a routine step.

    A settlement workflow is not defined by the rate quoted on a single conversion. It is defined by how predictably funds move from crypto balance to usable fiat, and how clearly the team can explain what happened.

    What a crypto-to-fiat settlement workflow needs to cover

    Before choosing tools or providers, map what the workflow actually has to answer. Most crypto businesses need to think about six connected areas:

    1. Conversion triggers and timing

    The team needs a clear answer to “when do we convert?” Common approaches include converting on a schedule (for example, weekly), above a balance threshold, or ahead of known obligations such as payroll dates. Deciding the trigger in advance turns settlement from a judgment call into a repeatable policy.

    2. Execution and routing

    Execution covers where the conversion happens and how funds move after it: which account receives the fiat, which entity it belongs to, and whether it settles directly into a payout-ready balance. Routing decided at execution time — rather than in advance — is a common source of delays and reconciliation gaps.

    3. Destination accounts

    Fiat that cannot be used is not settled. The destination account needs to support the currencies the business pays in and connect to the payout workflows — local transfers or SWIFT — that the business actually uses.

    4. Approvals and controls

    Conversions move real value. The workflow should define who can execute a conversion, who approves amounts above a threshold, and what evidence remains afterwards. Without that model, settlement depends on individual memory and chat history.

    5. Records and reconciliation

    Every conversion should capture the amount converted, the rate applied, the fees taken, the timestamp, and the destination reference. When those records are captured automatically, reconciliation becomes a review task instead of a rebuild task.

    6. Treasury context

    Settlement decisions should sit inside treasury visibility: balances across crypto and fiat, what is committed, what is available, and what is needed for upcoming obligations. A conversion executed with full context rarely surprises anyone.

    Where settlement usually breaks down

    A settlement workflow can look fine at low volume and still fail as the business grows. The common failure points:

    • The rate recorded by finance does not match the rate actually applied at execution.
    • Converted fiat lands in an account that is not connected to payouts, forcing an extra internal transfer.
    • No one owns the “when to convert” decision, so timing drifts week to week.
    • Fees are spread across the exchange, the receiving account, and the payout rail, making true cost hard to total.
    • Reconciliation is rebuilt manually from statements and screenshots.
    • Payout dates and settlement dates are managed separately, so payments wait on funds that exist but are not yet usable.

    None of these are conversion problems. They are workflow problems — and they are solved by designing the path, not by chasing better rates on individual trades.

    A practical settlement workflow, step by step

    Step 1: Define the conversion trigger

    Write down the policy: convert weekly, convert above a set threshold, or convert ahead of obligations. The policy should be boring enough that anyone on the team can predict what will happen.

    Step 2: Decide the destination before converting

    Before executing, confirm which account receives the fiat, in which currency, and whether that balance is payout-ready. If the answer requires a second transfer after conversion, plan that handoff as part of the workflow.

    Step 3: Set the approval model

    Decide thresholds, approvers, and what gets logged. Keep it proportional: routine conversions under policy run without friction, while larger or unusual conversions get explicit review.

    Step 4: Capture rate, fees, and references at execution

    Record what was converted, the rate applied, the fees, and the destination reference at the moment of execution. This single habit removes most month-end reconciliation work.

    Step 5: Review the workflow as volume grows

    Revisit triggers, thresholds, and destinations monthly. Settlement needs change with payroll size, supplier mix, and market conditions — the workflow should change with them deliberately rather than by drift.

    Where Cyrafa fits

    Cyrafa is built around crypto-to-fiat settlement as a business workflow rather than a one-off trade. Its platform turns digital asset balances into payout-ready fiat while keeping approvals, treasury visibility, and settlement paths connected — with transparent execution, routing guided by policy, and balances that settle into payout-ready funds.

    The related platform pages cover Business IBANs, crypto payment workflows, crypto-to-fiat exchange, SWIFT transfers, treasury management, and payouts. Teams can start with a single settlement path and expand as their operation grows.

    Corporate Cards are currently marked as Coming Soon, so businesses should evaluate the available account, conversion, settlement, and treasury workflows based on their current needs.

    Questions to ask about your current settlement path

    Before adding another provider or process:

    • Can the team explain, for any conversion last month, the rate applied and the fees paid?
    • Does converted fiat settle where payouts are executed from?
    • Is there a defined trigger for when to convert, or is it decided ad hoc?
    • Do approvals exist for conversions, and are they auditable?
    • Does reconciliation depend on manual statement matching?
    • Would a new entity, currency, or payout destination require rebuilding the workflow?

    The answers usually point to the same place: the gap between conversion and usable funds.

    Final takeaway

    Good crypto-to-fiat settlement is predictable. The trigger is defined, the destination is known, the approvals are clear, and the records exist.

    Start with the trigger policy. Decide destinations before executing. Add approvals proportionate to value. Capture rate and fees at execution. Then choose a platform that keeps conversion, treasury, and payouts connected instead of split across providers.

    Ready to review your crypto-to-fiat settlement path? Talk to the Cyrafa team.

  • Business IBAN vs Traditional Bank Account: What Growing Companies Should Know

    Business IBAN vs Traditional Bank Account: What Growing Companies Should Know

    As a company expands into new markets, its banking needs usually become more complex. Customers may pay from different countries, vendors may need international payouts, and finance teams may need clearer visibility across currencies and entities.

    At that stage, many businesses start asking whether a traditional bank account is still enough or whether a Business IBAN could provide a more practical operating structure.

    The answer depends on the company’s payment flows, operating model, and growth plans. A Business IBAN is not a replacement for every banking relationship. It is a business payment and account workflow that can help companies collect, route, and manage funds with more clarity.

    What is a traditional business bank account?

    A traditional business bank account is an account provided by a bank for receiving, holding, and sending business funds. It may support local payments, international transfers, cards, cash management, and other banking services depending on the institution and jurisdiction.

    Traditional accounts can be a strong foundation for a company’s finance operations. However, the experience can become more difficult when a business needs multiple currencies, cross-border collections, faster operational visibility, or workflows that involve crypto and fiat.

    The main challenge is not necessarily the account itself. It is the gap between the account and the rest of the company’s financial operations.

    What is a Business IBAN?

    A Business IBAN is a business-focused account identifier designed to support payment collection and routing through international banking workflows. It can give a company a clearer destination for business payments and help organize incoming funds around a defined operating structure.

    Depending on the provider and setup, a Business IBAN may support:

    • Business payment collections
    • International transfers
    • Currency-specific receiving workflows
    • Payment references and transaction tracking
    • Treasury and payout operations
    • Connection to broader finance processes

    The exact availability, currencies, jurisdictions, and services depend on the provider and the business’s onboarding requirements. Companies should always confirm the applicable terms before relying on a specific payment route.

    Business IBAN vs traditional bank account

    The difference is best understood through the way each option fits into the wider finance workflow.

    1. Payment collection

    A traditional account may work well for local collections, but international customers can face more friction when they need to send funds through unfamiliar or expensive routes.

    A Business IBAN can provide a clearer business payment destination for relevant international workflows. This may make it easier for customers and partners to understand where payments should be sent and for the finance team to identify incoming transactions.

    2. Cross-border operations

    Traditional banks often provide international transfers, but the process can involve different instructions, correspondent-bank steps, fees, and processing times.

    A Business IBAN can be part of a more structured cross-border collection and routing model. It does not remove every banking requirement, but it can help the business organize the entry point for international funds.

    3. Visibility and reconciliation

    When payments arrive without consistent references or clear ownership, reconciliation becomes a manual exercise. The team may need to match bank statements with invoices, emails, spreadsheets, and internal messages.

    A stronger Business IBAN workflow can help keep payment references and transaction context closer to the collection process. The goal is not simply to receive money. It is to know what the money is, where it came from, and what should happen next.

    4. Integration with crypto and fiat flows

    Many modern businesses operate across both digital assets and traditional currencies. A traditional bank account may handle fiat, while crypto activity sits somewhere else entirely.

    For a company with both types of flow, the important question is how the accounts, conversions, settlement, treasury, and payouts fit together operationally. A Business IBAN can become one part of a broader finance stack that connects business collections with related crypto-to-fiat and treasury workflows.

    5. Team controls

    As the company grows, finance tasks are shared across founders, finance managers, operations teams, and reviewers. A business account should fit a clear model of permissions, approvals, transaction limits, and reporting.

    The account alone does not create control. The surrounding workflow does.

    When should a growing company consider a Business IBAN?

    A Business IBAN may be worth considering when one or more of these situations apply:

    • The company receives regular payments from international customers.
    • Customers or partners find the current payment instructions confusing.
    • Finance spends too much time matching incoming payments manually.
    • The business operates in more than one currency.
    • Vendor and contractor payouts are becoming harder to coordinate.
    • The company needs a clearer separation between collections, treasury, and operating spend.
    • Crypto and fiat workflows are managed through disconnected systems.
    • The finance team needs better transaction context and reporting.

    These are not signs that a traditional bank account is unusable. They are signs that the business may need a more structured operating layer around its accounts.

    A Business IBAN is not a shortcut around compliance

    Businesses should not treat a Business IBAN as a way to avoid normal onboarding, verification, or financial controls. Providers may request company information, ownership details, expected activity, source-of-funds information, and other documentation.

    The right account structure is one that fits the company’s actual activity and can be operated transparently. Before onboarding, confirm the provider’s terms, supported countries, available currencies, transfer rails, and compliance requirements.

    How Cyrafa approaches business account workflows

    Cyrafa is designed for businesses that need to manage crypto and fiat operations through a more connected finance workflow. Its platform includes Business IBAN workflows alongside crypto payments, crypto-to-fiat exchange, SWIFT transfers, treasury management, and payouts.

    This approach is useful for companies that do not want to treat collections as an isolated banking task. Incoming payments, settlement decisions, treasury visibility, approvals, and outgoing payouts all affect one another.

    Cyrafa can help businesses start with the workflow that matters most and expand their operating model as their needs grow. Availability and suitability depend on the business profile, onboarding review, and applicable product terms.

    Questions to ask before choosing an account structure

    Before opening another account, ask:

    1. Which countries and currencies do we need to support?
    2. How will customers identify their payments?
    3. How will the finance team reconcile incoming funds?
    4. Who can view, approve, and execute transactions?
    5. How will the account connect to treasury and payout workflows?
    6. What reporting and transaction history will the business need?
    7. What are the provider’s onboarding, compliance, and usage requirements?

    The answers will help you choose an account structure based on real operations rather than on the account name alone.

    Final takeaway

    A traditional business bank account can remain an important part of a company’s financial foundation. A Business IBAN can add a clearer structure for international collections, routing, references, and connected payment operations.

    For growing companies, the decision should focus on the complete money flow: how funds are received, identified, settled, held, approved, and paid out.

    If your business is expanding across borders or operating across crypto and fiat, Cyrafa can help you explore a more connected approach to business accounts, treasury, transfers, and payouts.

    Want to review your current payment flow? Talk to the Cyrafa team.

  • How to Build a Finance Stack for a Global Web3 Company | Cyrafa

    How to Build a Finance Stack for a Global Web3 Company | Cyrafa

    Global Web3 companies rarely operate through one payment rail or one currency. They may collect fiat from customers, receive digital assets, pay global contributors, settle with vendors, manage treasury balances, and move funds across borders.

    That flexibility creates opportunity, but it can also create operational friction. When every workflow lives with a different provider, the finance team spends more time switching between systems, checking balances, confirming payment status, and rebuilding transaction context.

    A strong Web3 finance stack is not defined by the number of accounts or tools it contains. It is defined by how clearly the business can move, control, and understand its money.

    What a modern Web3 finance stack needs to handle

    Before selecting providers, map the money flow across the business. Most global Web3 companies need to think about six connected areas:

    1. Business collections

    The company needs a clear way to receive business payments and identify where each payment belongs. A dedicated business account structure can make collection, routing, and reconciliation easier to manage than a collection of informal or disconnected arrangements.

    2. Crypto payment acceptance

    Some customers and partners prefer to pay in digital assets. A crypto payment workflow should be considered alongside the company’s settlement process, not as an isolated checkout feature. The important questions are practical: How is the payment recorded? Where does the balance go? How does the team convert or settle it when needed?

    3. Crypto-to-fiat settlement

    Web3 businesses often need to move between crypto and fiat as part of normal operations. The finance team should understand the intended conversion path, the destination account, the timing of settlement, and the records required for reconciliation.

    4. Treasury visibility

    Knowing a balance is not the same as knowing the company’s usable liquidity. Treasury visibility means understanding balances across relevant accounts and assets, what is committed, what is available, and what needs to be moved for upcoming obligations.

    5. Global transfers and payouts

    Vendors, employees, contractors, partners, and customers may all require different payout routes. International transfer workflows, including SWIFT where appropriate, need clear ownership and status tracking so that operations teams are not forced to chase updates across multiple inboxes and dashboards.

    6. Controls and reporting

    As the team grows, payment execution should not depend on one person’s memory. Roles, permissions, approvals, transaction history, and reporting help finance and operations teams work from the same context.

    The problem with a fragmented stack

    A fragmented stack can appear efficient at the beginning. One provider handles an account, another handles crypto payments, a spreadsheet tracks treasury, and a messaging app carries approval requests.

    The friction usually appears later:

    • The same transaction has to be checked in more than one system.
    • Finance and operations see different versions of the current balance.
    • Approval decisions are difficult to audit.
    • Payout status depends on manual follow-up.
    • Month-end reconciliation takes longer as transaction volume grows.
    • A change in one provider creates work across the rest of the stack.

    The answer is not always to replace every provider immediately. A better first step is to identify the handoffs that create the most risk and delay, then design a clearer operating layer around them.

    A practical framework for building the stack

    Step 1: Draw the current money map

    Document how money enters, moves through, and leaves the business. Include customers, exchanges, wallets, business accounts, vendors, payroll, and treasury destinations.

    For each flow, record:

    • Currency or asset
    • Sending and receiving party
    • Account or wallet used
    • Approval owner
    • Expected settlement time
    • Reconciliation method

    This simple map often reveals that the biggest problem is not the payment itself. It is the missing context around the payment.

    Step 2: Separate collection, settlement, and treasury decisions

    These are related but different jobs. Collection answers how the business receives funds. Settlement answers how funds become usable in the required currency or account. Treasury answers how the business holds and allocates liquidity.

    Keeping these decisions separate makes it easier to choose the right workflow for each one.

    Step 3: Define the approval model

    Decide which payments require review, who can approve them, and what evidence should remain after execution. A clear approval model should work for recurring payouts as well as exceptional transactions.

    Step 4: Make reconciliation part of the workflow

    Reconciliation should not be a cleanup task at the end of the month. Capture transaction references, purpose, counterparty, status, and account context as close to execution as possible.

    Step 5: Choose a connected operating layer

    Once the money map is clear, look for a platform that can bring the relevant workflows into one business-facing operating layer. The goal is not to force every activity into one product. The goal is to reduce unnecessary switching and keep control, visibility, and execution close together.

    Where Cyrafa fits

    Cyrafa is designed for businesses that operate across crypto and fiat workflows and need a clearer way to manage business finance. Its platform pages cover Business IBANs, crypto payment workflows, crypto-to-fiat exchange, SWIFT transfers, treasury management, and payouts.

    The platform is also designed around practical operating needs such as permissions, approvals, transaction visibility, and reporting. This helps teams start with a specific workflow and expand as their finance operation becomes more complex.

    Corporate Cards are currently marked as Coming Soon, so businesses should evaluate the available account, payment, settlement, and treasury workflows based on their current needs.

    Questions to ask before changing your stack

    Before adding another provider, ask:

    1. Can the finance team see the full status of a transaction without checking several systems?
    2. Are crypto and fiat balances understood in the same operating context?
    3. Can the business explain who approved a payout and why?
    4. Are international transfers and vendor payouts easy to track?
    5. Does the current setup scale with more entities, currencies, and team members?
    6. Which workflow creates the most manual work every week?

    The answers will show where to start. A finance stack does not need to become complex just because the business is global. It needs to become more connected as the money flow becomes more diverse.

    Final takeaway

    The best finance stack for a global Web3 company is the one that gives the team a clear view of its money and a controlled way to move it.

    Start with the money map. Separate collections, settlement, and treasury decisions. Add clear approvals and reconciliation. Then choose the operating layer that can bring the most important workflows closer together.

    For businesses managing crypto, fiat, global transfers, and payouts, Cyrafa provides a starting point for building that more connected workflow.

    Ready to map your current finance flow? Talk to the Cyrafa team.


  • How to Choose a Payment Provider for a Forex Brokerage

    How to Choose a Payment Provider for a Forex Brokerage

    Choosing a payment provider for a forex brokerage is not simply a comparison of transaction fees or supported payment methods. The provider must fit the brokerage’s entities, currencies, client funding model, withdrawal process, treasury controls, compliance requirements, reconciliation workflow, and expected transaction volume. A weak fit can create failed payments, trapped liquidity, manual exceptions, and an expensive migration later.

    The right choice starts with the brokerage’s operating model—not a provider’s feature list. This guide gives broker finance, operations, compliance, and product teams a practical framework for defining requirements, comparing providers, running due diligence, and completing a controlled pilot before committing meaningful payment volume.

    Why forex brokerages need a different evaluation process

    A generic payment-provider checklist rarely captures the complexity of broker operations. Forex businesses may collect client funds, process withdrawals, pay partners, move liquidity between accounts, convert crypto and fiat, and settle across currencies and jurisdictions. These flows do not all have the same risk, urgency, approval requirements, or data needs.

    The choice also affects more than checkout conversion. A provider can shape:

    • how quickly operations can identify and route incoming funds;
    • how finance teams control withdrawals and bulk payouts;
    • where working balances must be held;
    • how fees and foreign-exchange differences are recorded;
    • how compliance teams review transactions and counterparties;
    • how easily transactions can be reconciled; and
    • how the brokerage responds when a rail or provider becomes unavailable.

    This is why the evaluation team should include finance, treasury, operations, compliance, technology, customer support, and the business owner for each payment flow. Procurement alone should not decide.

    First, define what the provider must actually do

    Before contacting vendors, map the required flows. Separate current requirements from expected needs over the next 12 to 24 months. Otherwise, attractive but irrelevant features can outweigh operational gaps.

    For each flow, document:

    • payer or beneficiary type;
    • originating and receiving legal entity;
    • countries or markets involved;
    • currency or digital asset;
    • expected transaction count and value;
    • peak-volume assumptions;
    • payment rail;
    • acceptable settlement window;
    • approval model;
    • required references and reports; and
    • refund, return, rejection, or exception process.

    A brokerage could group its flows into four categories.

    1. Client collections

    Define how clients fund accounts, how the brokerage identifies the sender, when funds become available, and when the trading ledger is credited. Ask whether collection accounts, business-account workflows, or crypto payment instructions can preserve the references needed to connect a payment to the correct client and entity.

    2. Client withdrawals

    Document beneficiary validation, approval thresholds, cut-off times, payout currencies, destination rules, and the evidence required to confirm completion. A fast initiation time is not useful if the brokerage cannot see whether a payment is pending, rejected, returned, or settled.

    3. Partner and operating payouts

    Introducing brokers, affiliates, vendors, and other partners may require scheduled or bulk payments. Evaluate whether the workflow supports batches, multi-user approval, status tracking, and downloadable transaction records.

    4. Treasury and settlement

    Map how balances move between collection, operating, safeguarding where applicable, settlement, and treasury accounts. If the brokerage uses both crypto and fiat, include conversion, liquidity access, network selection, and the ownership of fees and exchange-rate decisions.

    If this architecture is not yet defined, begin with Cyrafa’s guide to building a forex broker payment stack. The provider-selection exercise should test candidates against that architecture rather than allow a vendor to define it by default.

    Eleven criteria for comparing forex payment providers

    1. Entity, market, currency, and rail coverage

    “Global coverage” is too vague for due diligence. Request a written matrix showing which of your legal entities can be onboarded, which currencies or assets are supported, and which flows are available for each market.

    Confirm the difference between:

    • the countries where the provider can onboard the brokerage;
    • the locations from which payments can originate;
    • the destinations to which funds can be sent;
    • the currencies that can be held, received, sent, or converted; and
    • the rails available for collections, transfers, and payouts.

    Do not assume that support for a currency means the provider can collect, hold, convert, and pay it out in every required entity. Ask for the complete route.

    2. Fit for deposits, withdrawals, and payouts

    A provider may perform well for one flow and poorly for another. Score collections, withdrawals, partner payouts, and treasury transfers separately.

    For every flow, request a lifecycle diagram and a status list. The provider should explain what each status means, which events are final, how reversals are represented, and how your system receives updates. This matters because “processed” may mean an instruction was accepted rather than that the beneficiary received funds.

    3. Settlement model and liquidity impact

    Provider selection is also a treasury decision. Ask where funds are held, when they are available, which balances must be prefunded, and whether reserves, limits, or settlement delays can apply.

    Build a daily liquidity model using realistic volumes. Include:

    • opening balance requirements;
    • expected client inflows and withdrawals;
    • conversion timing;
    • provider cut-off times;
    • weekends and local holidays;
    • pending or returned transactions; and
    • concentration limits by account, provider, currency, or asset.

    A low transaction fee can be outweighed by the cost of maintaining excess balances across several disconnected accounts. Cyrafa’s treasury management page explains how balance visibility, approvals, and settlement context can sit closer to payment execution.

    4. Complete pricing—not the headline fee

    Request pricing for the specific routes in your requirements matrix. Compare the expected total cost of ownership rather than a single percentage.

    The model should include, where applicable:

    • setup or onboarding fees;
    • monthly minimums;
    • incoming and outgoing transaction fees;
    • currency-conversion costs and spreads;
    • blockchain network or withdrawal fees;
    • SWIFT or intermediary-bank charges;
    • return, rejection, recall, or investigation fees;
    • account or balance fees;
    • reporting or API charges; and
    • internal staff time spent on exceptions and reconciliation.

    Run at least three scenarios: expected volume, peak volume, and a stress case with more failures or manual reviews. Require the provider to state which charges are fixed, variable, passed through, or subject to change.

    5. Compliance and onboarding alignment

    The question is not whether a provider says it is “compliant.” Ask what it needs from your brokerage, which entities perform each service, and how the control model works in practice.

    Review:

    • contracting and service-providing entities;
    • licences or registrations relevant to the proposed service and location;
    • supported customer and business models;
    • onboarding documents and expected refresh cycles;
    • transaction-monitoring responsibilities;
    • sanctions and screening responsibilities;
    • source-of-funds or source-of-wealth escalation processes;
    • restricted countries, activities, assets, and counterparties;
    • information required for bank and crypto transfers; and
    • account restriction, suspension, and termination procedures.

    Where virtual assets are involved, risk assessment should be specific to the assets, products, counterparties, delivery channels, and markets in the proposed flow. The FATF’s updated guidance for virtual assets and virtual asset service providers explains the risk-based approach and the application of relevant anti-money-laundering and counter-terrorist-financing measures to this sector.

    The brokerage should obtain its own legal and compliance advice. A provider relationship does not transfer the brokerage’s obligations to the vendor.

    6. Controls, permissions, and approvals

    Ask the provider to demonstrate the control model rather than describe it. Test whether the platform can support:

    • separate roles for creators, approvers, reviewers, and administrators;
    • multi-user approval for sensitive payments;
    • amount-based or workflow-based approval rules;
    • entity and account separation;
    • beneficiary management controls;
    • audit logs for user and transaction actions;
    • API credential permissions and rotation; and
    • alerts for unusual or high-value activity.

    The workflow should reflect how your teams operate. Shared logins, approval through chat messages, or manual evidence stored outside the payment system create avoidable control gaps.

    7. Integration quality

    An API checklist should cover the entire transaction lifecycle, not only payment creation. Ask for sandbox access and test:

    • account and balance retrieval;
    • payment initiation;
    • idempotency and duplicate prevention;
    • webhooks or event notifications;
    • status changes and finality;
    • fees and exchange-rate fields;
    • batch or bulk instructions;
    • beneficiary creation and validation;
    • refunds, returns, recalls, and rejections;
    • rate limits and retry behaviour; and
    • report exports and historical retrieval.

    Check how breaking changes are communicated and how long older API versions remain supported. The provider should also explain the process for planned maintenance and emergency changes.

    8. Reconciliation and reporting

    Every provider demo should include a reconciliation exercise using sample transactions. Confirm that each payment includes stable identifiers and that reports contain gross amount, net amount, currency, fees, timestamps, status, entity, account, and external references.

    Ask whether reports can be generated through the interface and API, whether historical data remains accessible, and whether adjustments appear as new events rather than silent changes.

    Use the practical controls in Cyrafa’s forex broker payment reconciliation guide to test whether the provider’s data can support daily matching and exception management.

    9. Security and operational resilience

    Request evidence appropriate to the service, not just a security logo on a sales deck. Review access controls, encryption, credential management, security testing, incident response, recovery arrangements, subcontractor dependencies, and data-retention practices.

    Then test operational failure scenarios:

    • API or portal unavailability;
    • delayed webhooks;
    • a bank or blockchain rail outage;
    • incorrect status reporting;
    • frozen or restricted transactions;
    • compromised user credentials;
    • provider-side processing backlogs; and
    • loss of access to reports during an investigation.

    Ask for incident notification targets, escalation contacts, recovery objectives, and the evidence supplied after an incident. Service uptime alone does not describe whether payments, balances, and reporting remain usable.

    10. Support and exception handling

    Support quality is most visible when a high-value payment is missing or a withdrawal batch is delayed. Request the support model in writing:

    • service hours and time zones;
    • standard and urgent channels;
    • severity definitions;
    • first-response and resolution targets;
    • escalation path;
    • named relationship contacts, if included;
    • languages supported; and
    • investigation evidence required from the brokerage.

    During the pilot, submit realistic questions and record the clarity, ownership, and response time. A polished sales process does not prove effective operations support.

    11. Contract terms, concentration, and exit readiness

    Commercial due diligence should cover service scope, limits, liability, data access, subcontracting, pricing changes, reserve or balance conditions, termination rights, and the treatment of pending transactions after termination.

    Avoid designing a workflow that cannot be moved. The brokerage should know how it would:

    • export transaction and beneficiary data;
    • settle or withdraw remaining balances;
    • handle payments still in progress;
    • redirect client instructions;
    • revoke API keys and user access;
    • retain required records; and
    • activate a backup route.

    Provider concentration is not automatically wrong, but it should be measured and approved. A second provider is useful only when the backup route has been onboarded, integrated, funded where necessary, and tested.

    A practical provider scorecard

    Use weighted scoring so that a small pricing advantage cannot hide a critical control or coverage gap. A starting model might look like this:

    Evaluation areaSuggested weightEvidence to request
    Entity, market, currency, and rail coverage15%Written route matrix and restrictions
    Flow and settlement fit15%Lifecycle maps, limits, cut-offs, funding model
    Compliance and onboarding15%Entity details, responsibilities, policies, restrictions
    Controls and security15%Live demo, audit logs, security and incident evidence
    Integration and data15%Sandbox tests, API documentation, sample events and reports
    Pricing and liquidity impact10%Full pricing schedule and scenario model
    Reconciliation and reporting5%Sample transaction and settlement files
    Resilience and support5%SLA, escalation route, continuity evidence
    Contract and exit readiness5%Draft agreement, data export and termination process

    Score each category from 1 to 5, multiply it by the weight, and attach evidence to every score. Mark non-negotiable requirements as pass/fail. A provider that fails an essential entity, compliance, security, or settlement requirement should not win through a high average elsewhere.

    Weights should reflect the brokerage’s actual model. A crypto-heavy business may place more weight on supported networks, wallet controls, conversion, and blockchain transaction data. A business using bank rails may prioritise collection-account structure, payment references, SWIFT visibility, and return handling.

    Questions to ask during an RFP or provider demo

    Use questions that require concrete answers:

    1. Which of our legal entities can you onboard, and which entity will contract with and serve each one?
    2. Show the complete route for each required currency or asset, from receipt to withdrawal or settlement.
    3. Which limits, reserves, prefunding rules, cut-off times, or settlement delays could apply?
    4. Which transaction statuses exist, and which status proves final settlement?
    5. How are fees, FX rates, intermediary charges, and network costs represented in reports?
    6. What information is returned when a payment is rejected, returned, recalled, or held for review?
    7. Can we assign different permissions and approval rules by user, entity, account, and amount?
    8. How do you prevent duplicate API instructions and recover from missed events?
    9. What is the escalation route for an urgent, high-value transaction?
    10. Which banks, processors, custodians, liquidity partners, or other subcontractors are critical to this service?
    11. What notice do you provide before a material service, pricing, API, or policy change?
    12. How do we export our full transaction history and move balances if the relationship ends?

    Record answers in the scorecard. Verbal statements that affect coverage, pricing, controls, or settlement should be confirmed in product documentation or the contract.

    Red flags that deserve further investigation

    Pause the evaluation when a candidate:

    • promises “global” access without a route-by-route coverage matrix;
    • cannot identify the contracting and service-providing entities;
    • quotes one headline price but will not disclose other charges;
    • uses ambiguous terms for settlement or transaction finality;
    • cannot provide sample reports before contracting;
    • offers an API without reliable status events or duplicate protection;
    • relies on shared accounts or weak user permissions;
    • cannot explain restricted flows or escalation procedures;
    • avoids questions about critical subcontractors or service dependencies;
    • has no credible process for exporting data and remaining funds; or
    • pressures the brokerage to commit volume before completing a realistic pilot.

    A red flag does not always require immediate rejection, but it requires evidence and an accountable decision before the provider receives live volume.

    Run a controlled pilot before migration

    A pilot should prove the provider’s operational fit, not merely show that one payment can be sent. Use a limited entity, route, currency, client group, or payout type and define success criteria in advance.

    Test normal and exception scenarios, including:

    • successful receipt and identification of funds;
    • approved withdrawal or partner payout;
    • incorrect or missing reference;
    • duplicate instruction;
    • rejected beneficiary or transaction;
    • return or reversal;
    • delayed status update;
    • fee and FX reconciliation;
    • user approval and audit trail;
    • support escalation; and
    • daily report export and matching.

    Measure completion time, failure rate, exception rate, manual touches, reconciliation lag, support performance, fee variance, and liquidity held. The pilot should end with a documented go, remediate, or reject decision.

    Do not move all volume on the first successful test. Increase it through controlled stages, confirm daily balances and exceptions, and retain a tested fallback until the new route is stable.

    How Cyrafa supports connected broker payment operations

    Cyrafa’s forex broker payment solutions are designed to coordinate client collections, settlement, treasury controls, and partner payouts across fiat and crypto rails. Broker teams can connect business-account workflows, bank transfers, crypto movement, bulk execution, and approval-ready controls inside one operating layer.

    Depending on the agreed operating model, related Cyrafa services include Business IBAN, SWIFT transfers, a crypto payment gateway, and crypto-to-fiat workflows. The objective is not to add every rail at once. It is to build a controlled workflow in which transaction visibility, approvals, treasury context, and execution stay connected as the brokerage grows.

    Choose on evidence, not promises

    The best payment provider for a forex brokerage is the one that fits the broker’s real entities and flows, produces usable transaction data, supports appropriate controls, explains its dependencies and restrictions, and performs under realistic operating conditions.

    Start with a requirements matrix. Compare full-route coverage and total cost. Test compliance responsibilities, permissions, reporting, resilience, and support. Then validate the result through a controlled pilot and preserve an exit route.

    Ready to evaluate a connected payment workflow for your brokerage? Talk to Cyrafa about your collections, settlement, treasury, and payout requirements.

  • Forex Broker Payment Reconciliation: A Practical Guide for Deposits and Withdrawals

    Forex Broker Payment Reconciliation: A Practical Guide for Deposits and Withdrawals

    Forex broker payment reconciliation is the process of proving that every deposit, withdrawal, fee, conversion, and settlement recorded by a payment provider matches the correct client, trading account, legal entity, and accounting entry. When it works, finance and operations share one reliable view of what moved. When it fails, the broker accumulates unmatched payments, incorrect client balances, support tickets, and month-end risk.

    The challenge becomes harder as the brokerage adds crypto payments, business accounts, SWIFT transfers, multiple currencies, and several payment providers. More rails create more ways for clients to fund and withdraw, but they also produce different references, statuses, fees, settlement schedules, and data formats.

    This guide explains how to build a reconciliation workflow that connects payment execution to client ledgers, approvals, treasury, and accounting. It also shows how Cyrafa’s forex broker payment solutions can keep collections, settlement, payouts, and transaction visibility inside one operating layer.

    What is payment reconciliation for a forex broker?

    Payment reconciliation compares records from separate systems and confirms that they describe the same transaction.

    For a typical client deposit, the broker may need to match:

    1. the client’s funding request;
    2. the bank, payment-provider, or blockchain transaction;
    3. the credit posted to the CRM or trading account;
    4. the provider’s fee and settlement amount;
    5. the movement into the broker’s business or treasury account; and
    6. the accounting entry for the correct legal entity.

    For a withdrawal, the broker may need to match:

    1. the client’s request;
    2. the approved amount and destination;
    3. the debit from the trading or client ledger;
    4. the outgoing provider instruction;
    5. the bank or blockchain settlement reference;
    6. fees and exchange-rate differences; and
    7. the final completed, rejected, returned, or pending status.

    Reconciliation is complete only when the records agree or an explained exception has been assigned to an owner. A transaction that appears in one system but not another is not reconciled merely because the total balance looks reasonable.

    Why reconciliation becomes difficult as a brokerage grows

    Small operations can sometimes investigate transactions manually. That approach breaks down when client volume, providers, currencies, entities, and payment methods increase.

    Multiple systems use different identifiers

    A single deposit may have a CRM request ID, provider transaction ID, bank reference, blockchain hash, client account number, and internal ledger entry. If the broker does not preserve the relationship between them, teams must search several portals to reconstruct the payment.

    Provider statuses do not mean the same thing

    “Created,” “authorised,” “confirmed,” “processed,” “sent,” and “settled” may represent different stages depending on the rail. A broker needs an internal status model that translates provider events into a consistent operational meaning.

    Fees and FX create amount differences

    The amount requested by the client may differ from the amount received, credited, converted, or settled. Network fees, provider charges, correspondent-bank deductions, spreads, and currency conversions must be recorded rather than treated as unexplained discrepancies.

    Settlement timing creates temporary breaks

    A client may be credited before the provider settles funds into the broker’s account. Some bank transfers and conversions complete on different schedules. The reconciliation process must distinguish a valid timing difference from a missing transaction.

    Different legal entities may share operations

    A brokerage group may operate across markets and entities while using common teams or systems. Every payment still needs the correct entity, account, purpose, and accounting treatment. Otherwise, an operationally successful payment can become an intercompany or reporting problem.

    The records every broker should connect

    A strong data model begins with a unique internal transaction ID. That ID should connect the client or business event to every later record, even when external providers use their own references.

    For each deposit or withdrawal, capture:

    • internal transaction ID;
    • client and trading-account ID;
    • legal entity;
    • transaction type;
    • payment method and provider;
    • original amount and currency or asset;
    • expected net amount;
    • fee components;
    • exchange rate and conversion amount where relevant;
    • source or destination details permitted by policy;
    • provider transaction reference;
    • bank reference or blockchain transaction hash;
    • initiated, approved, confirmed, and settled timestamps;
    • current internal and external statuses; and
    • exception reason and owner where applicable.

    Structured payment data supports automation. Swift describes ISO 20022 as an open global standard that provides rich, consistent, and structured financial information. Swift also highlights benefits including better analytics, less manual intervention, more accurate compliance processes, and enhanced straight-through processing. Even when a broker is not implementing the standard directly, the principle remains useful: better structured references create better reconciliation.

    A five-stage forex broker reconciliation workflow

    The process should run continuously through the payment lifecycle rather than wait until month-end.

    Stage 1: Capture the payment intent

    Create the internal transaction record before money moves. For a deposit, this may happen when the client chooses a funding method. For a withdrawal, it begins when the client submits the request.

    The record should state:

    • who initiated the payment;
    • what type of transaction it is;
    • the expected amount and asset or currency;
    • the selected provider and route;
    • the relevant client and entity; and
    • the reference that external systems should preserve.

    If the process begins with an unidentified incoming transfer, matching will always be harder.

    Stage 2: Ingest provider events

    Collect status updates and transaction data from the bank, crypto gateway, payment provider, or internal execution workflow. Where integrations are available, use event-driven or scheduled ingestion rather than manual downloads alone.

    Store the original provider reference and status, then map it to the broker’s internal status model. Do not overwrite earlier events; the history is valuable when a payment is disputed or delayed.

    Stage 3: Apply matching rules

    Matching rules compare the internal instruction with the external transaction. A high-confidence match can use several fields:

    • unique transaction or virtual-account reference;
    • client or trading-account identifier;
    • exact asset and network;
    • amount within an allowed tolerance;
    • currency;
    • source or destination;
    • provider; and
    • expected time window.

    Use the strongest identifiers first. Matching only by amount and date creates false positives when many clients fund similar amounts.

    Stage 4: Separate matches from exceptions

    Transactions that satisfy the rules can move through the normal reconciliation path. Anything uncertain should enter an exception queue rather than be forced into a match.

    The exception record should show:

    • what failed to match;
    • the affected client, entity, and provider where known;
    • the amount at risk;
    • the reason category;
    • the responsible team or person;
    • the next action; and
    • how long the item has been open.

    Stage 5: Confirm settlement and accounting

    A deposit is not fully reconciled just because the client account was credited. Confirm the provider settlement, fees, FX, and destination account. A withdrawal is not complete just because the instruction was released; confirm the final settlement or record the rejection or return.

    The accounting entry should reflect the correct gross amount, fees, currency movement, entity, and period. At this stage, finance should be able to trace the ledger entry back to the client or business event without rebuilding the story from emails.

    How to reconcile forex broker deposits

    Deposits create both customer-experience and financial-control risk. Crediting too slowly frustrates traders; crediting incorrectly exposes the broker.

    Bank and IBAN deposits

    A business IBAN workflow can provide clearer fiat collection routes, but reconciliation still depends on reliable payment references and account ownership data.

    Match:

    • expected funding request;
    • sender and beneficiary information available to the broker;
    • currency and amount;
    • reference or virtual-account data;
    • bank transaction status;
    • client credit; and
    • final settlement into the correct business account.

    Create an exception when the payment has no usable reference, comes from an unexpected source, uses the wrong currency, or differs from the expected amount.

    Crypto deposits

    A crypto payment gateway should connect the blockchain payment to the client funding request and make reconciliation more reliable than using a general shared wallet.

    Match:

    • invoice or deposit request ID;
    • client account;
    • assigned address or transaction reference;
    • token and blockchain network;
    • amount received;
    • transaction hash;
    • confirmation status;
    • credited amount; and
    • any conversion or network fees.

    A transaction on the wrong network, unsupported asset, incorrect amount, or shared address may require manual review. Do not credit solely because a wallet balance increased.

    Deposits with conversion

    When the client funds in one asset or currency and the trading account is credited in another, preserve both sides of the conversion:

    • original amount;
    • execution rate;
    • provider or spread cost;
    • converted amount;
    • credited amount; and
    • settlement destination.

    Cyrafa’s crypto-to-fiat workflow keeps conversion, treasury review, and payout-ready settlement close together, which can reduce the handoffs finance must trace later.

    How to reconcile forex broker withdrawals

    Withdrawals add approval and destination risk to the reconciliation process.

    Before release, connect the request to:

    • the verified client and trading account;
    • available and withdrawable balance;
    • approved amount and currency or asset;
    • verified bank account or wallet;
    • required compliance review;
    • approver; and
    • selected payment route.

    After release, match:

    • the internal withdrawal ID;
    • provider instruction;
    • outgoing account debit;
    • bank reference or transaction hash;
    • fees;
    • final recipient amount where available;
    • settlement timestamp; and
    • completed, rejected, returned, or pending status.

    Do not mark a withdrawal complete based only on an internal approval or submitted provider instruction. The internal status should reflect the strongest settlement evidence available for the rail.

    Reconciliation across SWIFT and cross-border transfers

    SWIFT transfers can support international settlement and payments, while approvals, treasury context, and status remain part of the operating workflow.

    Cross-border transfers may include correspondent banks, intermediary fees, cut-off times, and additional information requests. Reconciliation should therefore distinguish:

    • instructed amount;
    • debited amount;
    • fees paid by the sender;
    • intermediary or receiving deductions where known;
    • beneficiary amount;
    • value date;
    • transfer reference; and
    • final status.

    If the recipient reports a short payment, the team should be able to separate an agreed fee arrangement from an unexplained discrepancy.

    The exception queue: where reconciliation succeeds or fails

    Automation handles normal transactions. Operational quality is revealed by how the brokerage manages exceptions.

    Common exception types include:

    • payment received without a client reference;
    • duplicate provider event or duplicate credit;
    • amount outside tolerance;
    • unsupported asset, network, or currency;
    • incorrect or changed beneficiary details;
    • payment initiated by an unexpected third party;
    • provider says completed but the beneficiary reports non-receipt;
    • bank transfer returned;
    • blockchain transaction delayed or replaced;
    • provider fee or FX difference not recorded;
    • client credited but provider settlement missing;
    • payment assigned to the wrong entity; and
    • reversal, refund, chargeback, or compliance hold.

    Prioritise exceptions by risk

    Not every break has the same urgency. Rank items using:

    • client impact;
    • amount;
    • age;
    • withdrawal versus deposit;
    • compliance risk;
    • provider or balance exposure;
    • possibility of duplicate credit or payment; and
    • financial-close deadline.

    Give every exception one owner

    An exception should not sit between finance, operations, support, and compliance. Assign a current owner, required action, and escalation time. Ownership can change, but the history should remain visible.

    Close with evidence

    Do not resolve an exception by deleting it or changing the amount until totals match. Record what happened, who approved the resolution, which entries changed, and what evidence confirms the final outcome.

    Daily, intraday, and month-end reconciliation

    Different controls operate at different frequencies.

    Intraday monitoring

    Use for high-volume or time-sensitive flows. Monitor:

    • uncredited confirmed deposits;
    • approved withdrawals awaiting release;
    • provider failures;
    • unusual status delays;
    • duplicate events; and
    • balances approaching operational limits.

    Daily reconciliation

    At least daily, compare:

    • opening and closing provider balances;
    • transaction movements;
    • client credits and debits;
    • fees and conversions;
    • settlements received or paid;
    • unresolved exceptions; and
    • expected versus actual liquidity.

    Month-end close

    Month-end should confirm the daily process rather than replace it. Finance should reconcile:

    • provider statements;
    • bank and wallet balances;
    • client-money or internal ledgers as applicable;
    • treasury and settlement accounts;
    • fees and FX results;
    • intercompany balances;
    • aged exceptions; and
    • general-ledger control accounts.

    If the team begins investigating old individual transactions only at month-end, the daily process is not strong enough.

    Reconciliation controls that reduce errors and fraud

    Separation of duties

    The same person should not be able to create, approve, release, and reconcile a material withdrawal or adjustment without independent review.

    Controlled reference creation

    Generate references systematically and prevent users from casually reusing them. Unique identifiers are one of the strongest reconciliation controls.

    Immutable event history

    Preserve original provider events, internal status changes, approvals, and adjustments. Corrections should add history rather than erase it.

    Balance controls

    Reconcile individual transactions and aggregate balances. A transaction-level match can still be incomplete if the overall provider balance contains an unexplained difference.

    Adjustment governance

    Manual credits, reversals, fee corrections, and FX adjustments require a reason, supporting evidence, and approval. Track their frequency because repeated adjustments may expose an integration or process problem.

    Beneficiary and wallet controls

    Changes to withdrawal destinations deserve additional verification and should not be hidden inside the normal payment flow.

    Metrics for payment reconciliation

    Useful metrics include:

    • automatic match rate;
    • manual-intervention rate;
    • unmatched transaction value and count;
    • exceptions by reason, provider, rail, and entity;
    • average time to resolve an exception;
    • confirmed deposits awaiting client credit;
    • approved withdrawals awaiting settlement;
    • duplicate events or payments prevented;
    • aged reconciliation items;
    • manual adjustments by value and cause;
    • provider settlement variance;
    • payment-related support tickets; and
    • days required to complete month-end close.

    A high automatic-match rate is useful only if the matching rules are accurate. Review false matches as well as unmatched items.

    A reconciliation checklist for forex brokers

    Data and references

    • Does every payment have a unique internal transaction ID?
    • Can that ID be connected to provider, bank, blockchain, CRM, trading-account, and ledger records?
    • Are fees, FX, and settlement amounts stored separately from the original instruction?

    Status management

    • Are provider statuses mapped to one internal status model?
    • Is the distinction between submitted, confirmed, settled, rejected, and returned clear?
    • Is the complete event history retained?

    Matching

    • Do rules use strong identifiers before amount and time?
    • Are tolerances documented by rail and currency?
    • Are uncertain transactions routed to review rather than forced into a match?

    Exceptions

    • Does every exception have a reason, owner, priority, and next action?
    • Are client-impacting and high-risk breaks escalated quickly?
    • Is closure supported by evidence and approval?

    Governance

    • Are manual adjustments controlled?
    • Are legal entities and accounts clearly separated?
    • Are individual transactions and provider balances both reconciled?
    • Can finance reproduce the result for an audit or management review?

    How Cyrafa supports clearer broker payment operations

    Cyrafa connects client collections, business accounts, crypto movement, conversion, settlement, payouts, approvals, and treasury visibility inside one workflow.

    For broker teams, that means payment context can remain close to execution:

    • IBAN collections and bank transfers;
    • crypto deposits and withdrawals;
    • crypto-to-fiat settlement;
    • SWIFT and cross-border transfers;
    • partner and vendor payouts;
    • role-based approvals;
    • payment and settlement status; and
    • transaction history for reconciliation and reporting.

    The goal is not simply to move money. It is to make each movement explainable from the original request through final settlement.

    For the broader infrastructure model, read How to Build a Forex Broker Payment Stack. For high-volume business payments, see the guide to bulk payouts for forex brokers.

    Frequently asked questions

    How often should forex brokers reconcile payments?

    High-volume or client-impacting flows should be monitored intraday, while provider movements, client ledger entries, fees, and settlements should normally be reconciled daily. Month-end should validate the daily process and close remaining justified items.

    What is a three-way payment match?

    In a broker context, it can mean matching the client or business instruction, the external provider transaction, and the internal ledger or trading-account entry. Some workflows add a fourth layer by confirming final bank or treasury settlement.

    Can payment reconciliation be fully automated?

    Normal transactions with consistent identifiers and data can be matched automatically. Exceptions still require controlled review. The goal is high-quality straight-through matching plus an efficient exception process, not automation that hides uncertainty.

    How should crypto deposits be reconciled?

    Connect the deposit request to the assigned address or invoice, asset, blockchain network, amount, transaction hash, confirmation status, client credit, fees, and any later conversion or settlement. An increase in a shared wallet balance is not enough by itself.

    When is a withdrawal considered reconciled?

    When the approved client request, internal debit, provider instruction, destination, fees, and strongest available settlement evidence agree—or when any difference has been investigated, documented, and approved.

    What causes most unmatched payments?

    Common causes include missing or reused references, inconsistent identifiers, amount differences, fees, FX, timing, duplicate events, wrong networks, changed beneficiaries, and status mismatches between systems.

    Authoritative reference

    This article provides general information and does not constitute legal, regulatory, accounting, tax, or financial advice. Requirements and appropriate controls vary by jurisdiction, entity, provider, payment rail, and business model.

    Make every broker payment easier to explain

    Connect collections, withdrawals, settlement, approvals, and transaction visibility in one operating workflow. Talk to Cyrafa about your forex broker payment operations.
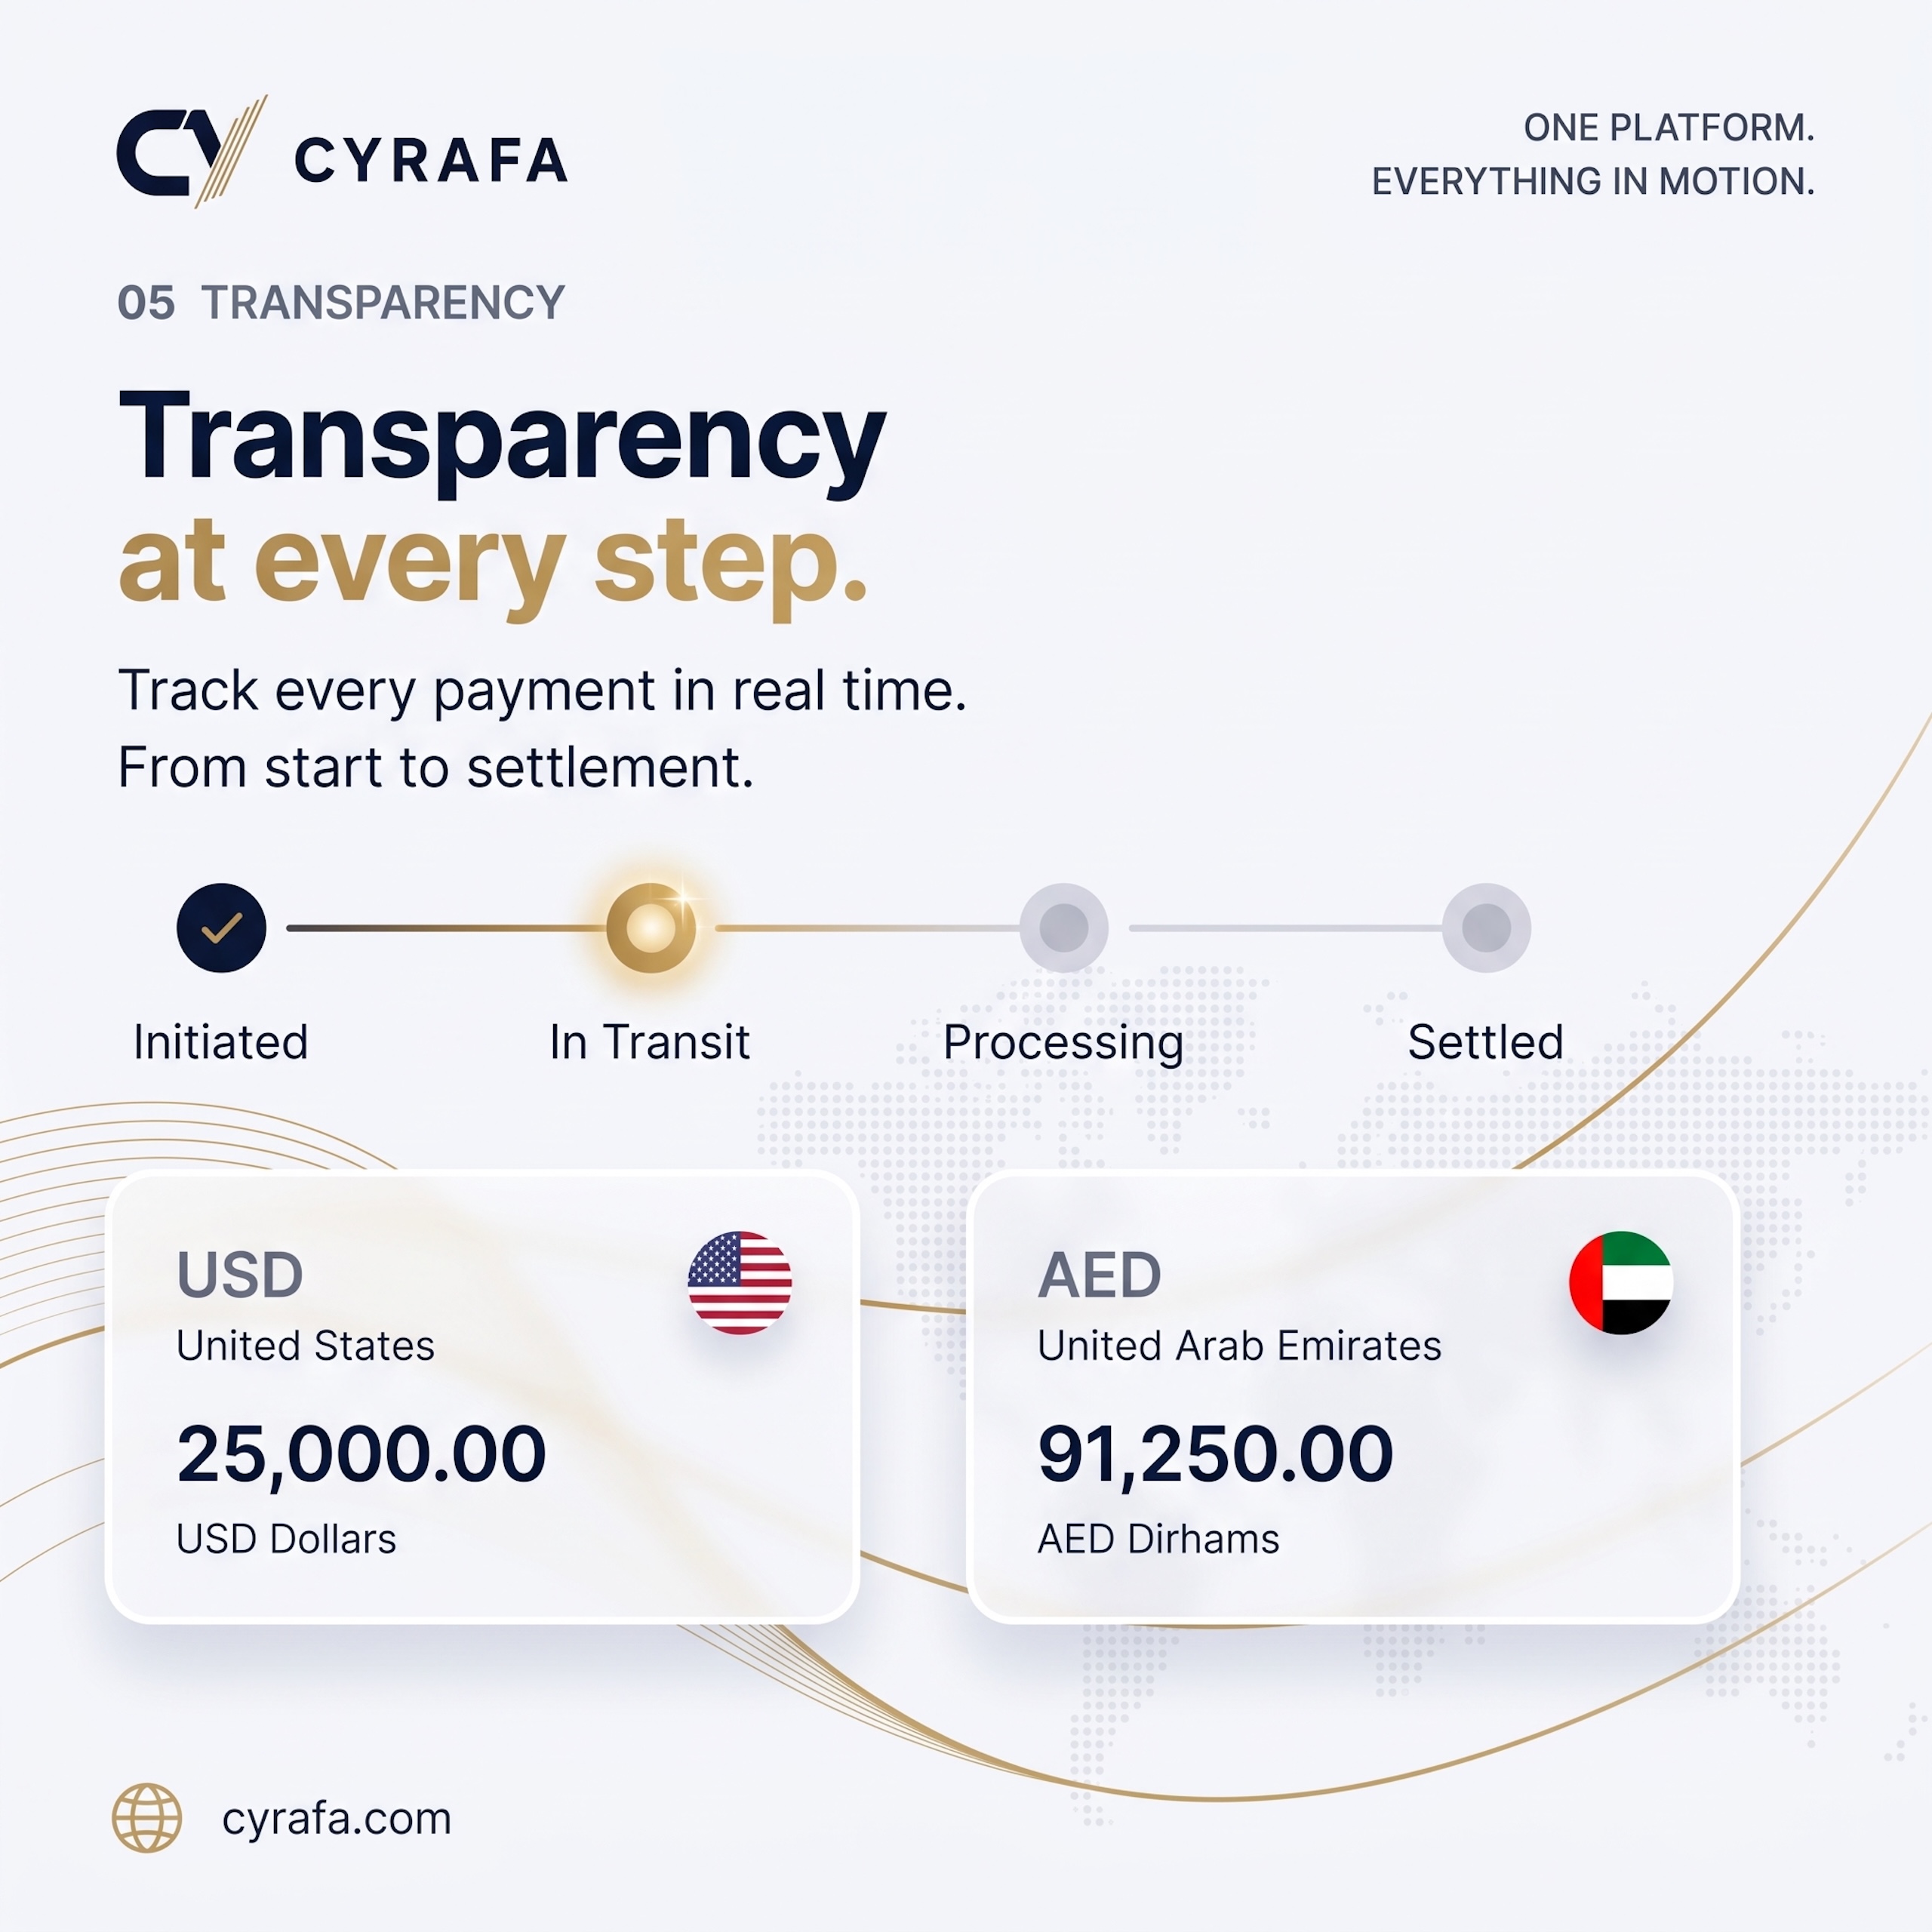
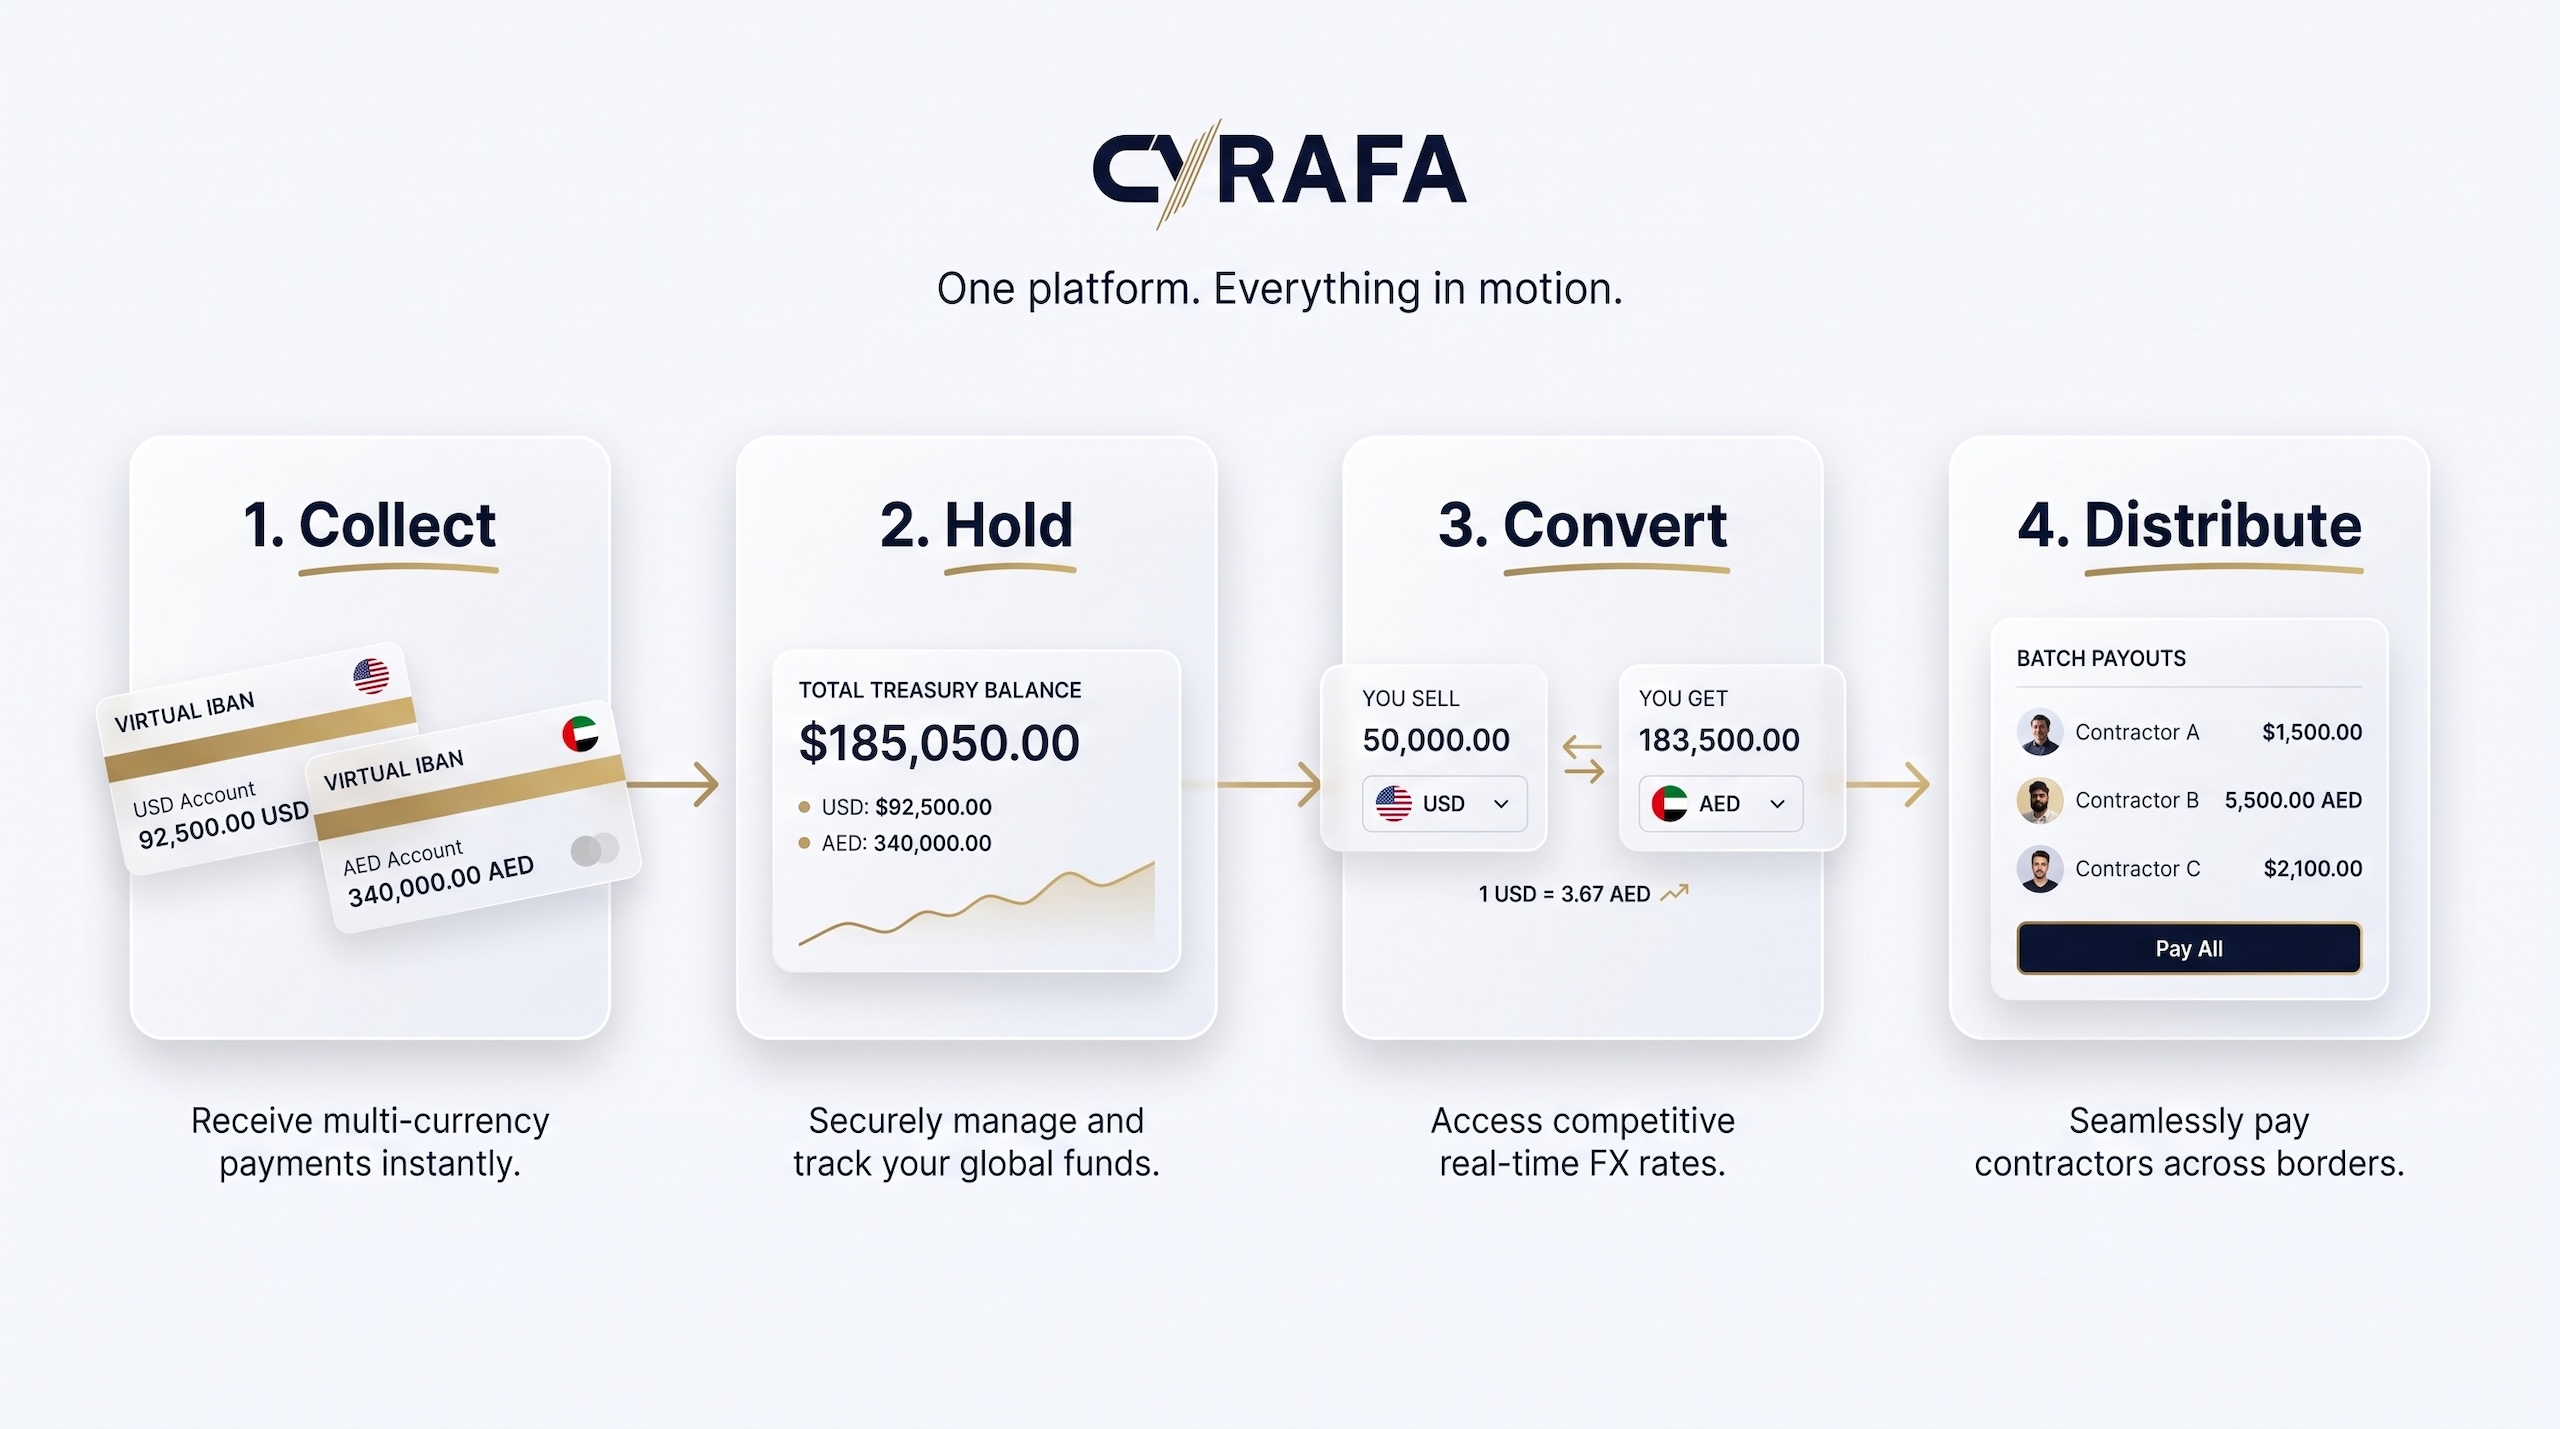
  • How to Build a Forex Broker Payment Stack: Crypto, IBAN, SWIFT, and Payouts

    How to Build a Forex Broker Payment Stack: Crypto, IBAN, SWIFT, and Payouts

    A forex broker payment stack is the connected set of payment rails, accounts, providers, controls, and records a brokerage uses to collect deposits, process withdrawals, settle funds, and pay partners. The strongest stack does not depend on one method. It combines crypto payments, business IBANs, SWIFT transfers, crypto-to-fiat settlement, and payout workflows around one operating model.

    That distinction matters. Adding more payment providers does not automatically create a stronger payment stack. If each rail has a separate dashboard, approval process, balance view, and reporting format, the broker gains payment options but also creates operational fragmentation.

    This guide explains how to choose the right rails, route each type of payment, reduce provider concentration, and keep execution connected to approvals, treasury visibility, and reconciliation. It also shows how Cyrafa’s forex broker payment solutions bring these workflows into one business-facing layer.

    What is a forex broker payment stack?

    A forex broker payment stack is the infrastructure and operating process behind the movement of money into, through, and out of a brokerage.

    It normally needs to support four different obligations:

    1. Client collections: receiving deposits through the payment methods available to the trader.
    2. Client withdrawals: returning funds through an approved route after the required checks.
    3. Business settlement: moving money between payment providers, business accounts, legal entities, and operating currencies.
    4. Partner and vendor payouts: paying introducing brokers, affiliates, suppliers, contractors, and other counterparties.

    These flows may share infrastructure, but they should not be treated as identical. A trader withdrawal has different approval, compliance, service, and reconciliation requirements from an affiliate commission or a supplier invoice.

    A complete stack therefore includes more than payment acceptance. It connects:

    • payment rails;
    • business accounts;
    • liquidity and conversion;
    • routing rules;
    • role-based approvals;
    • transaction monitoring;
    • settlement tracking;
    • reconciliation; and
    • exception management.

    Why one payment rail is not enough

    A brokerage that depends on a single payment rail creates a commercial and operational point of failure.

    Traders do not all use the same method

    Payment preferences vary by market, currency, transaction size, and customer profile. One trader may prefer stablecoins, another may need a bank transfer, while an institutional or high-value client may expect a named-account or SWIFT route.

    If the broker supports only one method, it limits who can fund and how quickly the business can enter a new market.

    Each rail solves a different problem

    Crypto payments can provide reach and out-of-hours movement. Business IBANs create a clearer route for fiat collections and settlements. SWIFT supports cross-border bank transfers. Crypto-to-fiat conversion turns digital-asset balances into currencies the business can use for payroll, suppliers, taxes, or partner payouts.

    The objective is not to declare one rail the winner. It is to assign each rail a defined job.

    Providers can become unavailable

    A payment provider can change its risk appetite, supported markets, pricing, or onboarding requirements. A bank or counterparty may delay a transaction or request additional documentation. Blockchain networks can face congestion, and a specific asset or chain may no longer fit the broker’s policy.

    A multi-rail stack gives the brokerage alternatives, but resilience only exists if those alternatives are onboarded, funded, tested, and operationally documented before they are needed.

    Cross-border payments still contain friction

    The Financial Stability Board identifies high costs, low speed, limited access, and insufficient transparency as persistent challenges in cross-border payments. A broker operating internationally cannot remove every external friction, but it can make routing, status, ownership, and reconciliation clearer inside its own organisation.

    The five layers of a broker payment stack

    A scalable payment stack can be understood as five connected layers. Weakness in any one of them creates manual work elsewhere.

    Layer 1: Collection rails

    This is how client funds enter the brokerage. The available routes may include crypto, local or international bank transfers, business IBANs, and other approved payment methods.

    The collection layer must answer:

    • Which currencies, assets, networks, and countries are supported?
    • How is each payment linked to the correct client and trading account?
    • What checks take place before the account is credited?
    • What happens when the amount, sender, currency, or reference does not match?
    • When is a deposit considered final and available for trading?

    A crypto payment gateway should turn an incoming blockchain transaction into a trackable payment event rather than leave the operations team matching public wallet transfers manually.

    Similarly, a business IBAN should sit inside a clear account and reconciliation structure so incoming fiat can be connected to the right entity, client, and purpose.

    Layer 2: Withdrawal and payout rails

    Money leaves the broker for several reasons, and the workflow must distinguish them.

    Client withdrawals require client-level checks, available-balance confirmation, destination validation, approval, and clear status communication.

    Partner and vendor payouts relate to commissions, contracts, invoices, or other business obligations. They require beneficiary records, payment-purpose data, entity allocation, approvals, and accounting references.

    High-volume partner payments can use a controlled bulk payout workflow instead of being initiated one at a time. The two payout types may use some of the same rails, but they should retain separate queues and records.

    Layer 3: Settlement and conversion

    Receiving money is not the end of the flow. The broker must place liquidity in the asset, currency, provider, and legal entity where it is needed.

    Settlement may involve:

    • moving collected funds into an operating account;
    • converting crypto balances into fiat;
    • converting between settlement currencies;
    • funding withdrawal or partner-payout pools;
    • paying suppliers through international banking rails; and
    • rebalancing exposure between providers and entities.

    A connected crypto-to-fiat workflow helps turn digital-asset balances into payout-ready fiat while keeping conversion, approval, and settlement context together.

    SWIFT transfers provide another route for international business settlement and partner payments. The broker still needs to track beneficiary details, fees, expected timing, transfer references, and final status.

    Layer 4: Control and compliance

    Every rail should operate within a consistent control model. Otherwise, the easiest method may become the least governed.

    Core controls include:

    • role-based permissions;
    • transaction and batch limits;
    • maker-checker approval;
    • verified beneficiary and wallet records;
    • sanctions and transaction screening where applicable;
    • source and purpose information;
    • new-address or new-account review;
    • exception escalation; and
    • a complete audit history.

    Compliance requirements vary by jurisdiction, customer type, payment method, and business activity. The operating model should allow controls to change by risk rather than forcing every payment through the same generic path.

    Layer 5: Ledger, reporting, and reconciliation

    The final layer explains what happened. It should connect the original business event to the payment instruction and final settlement.

    For each transaction, the broker should be able to identify:

    • the client, partner, vendor, or counterparty;
    • the responsible legal entity;
    • the business purpose;
    • the original and settlement currencies;
    • the amount, exchange rate, and fees;
    • the provider and payment rail;
    • the approval record;
    • the external transaction reference; and
    • the final accounting status.

    Without this layer, more payment methods create more month-end investigations.

    Crypto vs IBAN vs SWIFT: when should a broker use each?

    The correct choice depends on the payment rather than the popularity of the rail.

    RailBest suited toKey strengthsOperational considerations
    Crypto and stablecoinsCrypto-funded clients, approved digital-asset payouts, rapid movement between supported partiesBroad reach, availability outside banking hours, programmable transaction recordsNetwork selection, wallet verification, monitoring, conversion, price or issuer risk
    Business IBAN and bank transferFiat collections, operating balances, suppliers, named-account settlementFamiliar fiat workflow, bank-account documentation, business-purpose clarityCut-off times, supported countries, transfer references, banking review
    SWIFTCross-border fiat transfers and international counterpartiesGlobal banking reach and multi-currency settlementCorrespondent banks, fees, timing, beneficiary data, payment status
    Crypto to fiatTurning collected or treasury-held digital assets into spendable currenciesConnects digital-asset inflows to real business obligationsExecution price, settlement destination, approval, liquidity, reporting

    The stack should define a preferred and backup route for each major flow. The cheapest method is not always the best choice if it creates delays, weak references, reconciliation work, or a poor withdrawal experience.

    How to route deposits, withdrawals, settlement, and partner payouts

    Payment orchestration starts with routing rules. A routing rule decides where a payment should go based on known information instead of relying on ad hoc judgement every time.

    Route deposits by market and method

    For deposits, consider:

    • client jurisdiction;
    • supported currency or asset;
    • transaction size;
    • expected settlement time;
    • provider availability;
    • cost;
    • integration with the CRM or trading platform; and
    • the broker’s compliance policy.

    The system should also define what happens when the preferred route is unavailable. A fallback that exists only in a strategy document is not a real fallback.

    Route withdrawals by verified destination

    Withdrawals should be matched to an approved destination and reviewed under the broker’s policy. Routing should consider the original funding context, requested currency, available liquidity, provider status, and risk indicators.

    The customer-facing status must remain clear even if the payment passes through several internal stages.

    Route settlement by obligations

    Treasury should determine where balances are needed next. A broker may collect stablecoins but need fiat for a technology supplier, SWIFT settlement for an international counterparty, and separate liquidity for client withdrawals.

    The stablecoin treasury framework for trading businesses explains how balance limits, asset policy, conversion triggers, and reconciliation can support those decisions.

    Route partner payouts separately

    IB commissions, affiliate payments, and vendor invoices should retain their own approval and reconciliation context. They can then be grouped and executed through the appropriate bank, SWIFT, or crypto route without being mixed with client withdrawals.

    Avoiding provider concentration without creating provider chaos

    Using several providers can reduce dependency, but an uncontrolled multi-provider setup creates a different risk: fragmented operations.

    Define the purpose of every provider

    Each provider should have an explicit role, such as primary crypto collection, backup settlement, a particular fiat corridor, or international partner payouts. If two providers serve the same purpose, document how routing is decided.

    Set exposure limits

    Do not leave more operating liquidity with a provider than the workflow requires. Set thresholds by provider, asset, currency, and legal entity, then define who acts when the limit is exceeded.

    Test backup routes

    Periodically run a controlled payment through the fallback route. Confirm that credentials, beneficiary records, approvals, funding, and reconciliation still work.

    Keep one operational view

    Teams need a consolidated view of balances, pending actions, approvals, settlement status, and exceptions. Without it, the brokerage must manually reconstruct its position from separate portals.

    Approvals, reconciliation, and payment visibility

    A useful payment stack gives different teams the context they need without allowing everyone to do everything.

    Finance needs

    • balances and upcoming obligations;
    • exchange rates and fees;
    • legal-entity allocation;
    • approval evidence;
    • settlement confirmation; and
    • accounting exports.

    Operations needs

    • payment status;
    • failed or pending transactions;
    • recipient and destination details;
    • service timelines; and
    • clear next actions.

    Compliance needs

    • customer or counterparty context;
    • the source and purpose of funds;
    • screening and review evidence;
    • policy exceptions; and
    • a searchable audit trail.

    Leadership needs

    • liquidity by rail and provider;
    • payment cost and success rate;
    • concentration exposure;
    • aged exceptions; and
    • the impact of payment performance on growth and retention.

    The operating layer should connect these views to the same underlying transaction rather than maintain several conflicting versions of the truth.

    Metrics that show whether the stack is working

    Track performance by rail, provider, currency, country, and payment type. Useful metrics include:

    • deposit success rate;
    • time from payment initiation to trading-account credit;
    • withdrawal approval and settlement time;
    • failed, rejected, or returned payment rate;
    • manual-intervention rate;
    • average cost and FX cost per transaction;
    • provider and asset concentration;
    • liquidity held versus forecast obligations;
    • unreconciled transactions by age;
    • time required to resolve exceptions; and
    • payment-related support enquiries.

    A rail that appears cheap may be expensive after manual work, failed payments, support tickets, and delayed reconciliation are included.

    Forex broker payment stack checklist

    Use this checklist when designing the stack or assessing a provider.

    Coverage

    • Does it support the currencies, assets, networks, and markets the broker actually needs?
    • Can it handle collections, withdrawals, settlement, and partner payouts?
    • Are primary and backup routes defined for critical flows?

    Integration

    • Can transactions be linked to the correct client, trading account, partner, or invoice?
    • Does the workflow connect with the CRM, trading platform, finance records, or reporting process?
    • Are statuses and external references available without manual portal checks?

    Control

    • Can permissions and approvals vary by payment type, size, entity, and risk?
    • Are beneficiary and wallet changes controlled?
    • Can limits be applied by user, provider, asset, currency, and batch?

    Settlement and liquidity

    • Can the broker see where funds are held and what must settle next?
    • Is crypto-to-fiat conversion connected to the payout or settlement workflow?
    • Can the business fund and test backup routes?

    Reconciliation

    • Is every transaction assigned a unique reference?
    • Are fees, exchange rates, provider records, and settlement outcomes captured?
    • Can finance export an audit-ready history by entity and period?

    Exceptions

    • How are pending, rejected, returned, or mismatched payments handled?
    • Can one failed payment be repaired without recreating an entire batch?
    • Does every exception have a reason, owner, and next action?

    How Cyrafa connects the complete broker payment workflow

    Cyrafa is designed for broker teams that need crypto and fiat rails to work as one operational system.

    The workflow connects:

    • crypto collections and movement;
    • business IBAN and bank-transfer workflows;
    • SWIFT settlement;
    • crypto-to-fiat conversion;
    • client, partner, and vendor payment operations;
    • bulk execution;
    • role-based approvals;
    • treasury visibility; and
    • transaction history for reconciliation and reporting.

    Instead of adding another isolated payment dashboard, Cyrafa keeps execution close to balances, approvals, and settlement context. Teams can start with one workflow and expand without rebuilding the entire finance stack.

    Frequently asked questions

    How many payment providers should a forex broker use?

    There is no universal number. The broker needs enough coverage and redundancy for its markets without creating unnecessary operational complexity. Every provider should have a defined purpose, exposure limit, owner, and reconciliation process.

    Is a crypto payment gateway enough for a forex broker?

    It may cover crypto deposits and withdrawals, but the brokerage still needs business settlement, fiat accounts, supplier and partner payments, conversion, approvals, and reporting. A gateway is one component of the complete payment stack.

    Should deposits and withdrawals use the same provider?

    They can, but they do not have to. The decision should reflect supported corridors, liquidity, cost, reliability, compliance requirements, and the customer experience. The broker must preserve a clear audit trail across both flows.

    What is the difference between payment orchestration and adding providers?

    Adding providers creates more routes. Orchestration defines how those routes are selected, approved, funded, monitored, and reconciled. Without orchestration, more providers may simply create more manual work.

    How should a broker prepare for a provider outage?

    Maintain an onboarded and tested backup route, the required liquidity, verified beneficiaries, current access permissions, documented approval steps, and a communication process. Test the route before an outage occurs.

    Where do corporate cards fit?

    Corporate cards can eventually support controlled team and departmental spending, but they are separate from the core collection and client-withdrawal rails. Cyrafa currently presents corporate cards as coming soon, so they should be treated as a planned extension rather than a live dependency in the stack.

    Authoritative reference

    This article provides general information and does not constitute legal, regulatory, tax, or financial advice. Payment and virtual-asset requirements vary by jurisdiction, provider, customer type, and business model.

    Build a connected payment stack for your brokerage

    Bring crypto, IBAN, SWIFT, settlement, payouts, approvals, and treasury visibility into one controlled workflow. Talk to Cyrafa about your forex broker payment stack.